Thursday, May 14, 2015

389% Return for Melton Mowbray Buy To Let landlords since 2000?


Buy to let is essentially different from investing in stocks and shares or putting money in the Building Society. Whilst these other investments (Building Society Passbooks, Stocks and Shares etc) are passive  ie once the  money has been invested it you leave it alone, with buy to let, things are more hands on, in fact it’s almost a business. One thing the landlords I speak to say is the fact that they like buy to let because it is both an investment as well as a business. It is this factor that attracts many of my Melton Mowbray landlords – they are making their own decisions rather than entrusting them to others (such as City Whiz Kids in London playing roulette with their Pension Pot).

So if you are investing in the Melton Mowbray property market, you can earn from your investment in two ways. When a property increases in value over time, it is known as 'capital growth'. Capital growth, also known as capital appreciation, this has been strong in recent times in Melton Mowbray, but the value of property does go up as well as down just like shares do but the initial purchase price rarely decreases.  Rental income is what the tenant pays you - hopefully this will grow over time. If you divide the annual rent into the value (or purchase price) of the property, this is your yield, or annual return.

I was talking to a landlord who bought a semi-detached house in the Longfield Road area of Melton Mowbray. He bought a very pleasant 3 bed semi-detached in 2000 for £70,950. It sold again in January just gone for £140,000, a rise of 97.32% in just over 15 years – a compound annual return of 4.64%.

However, the real returns are for those Melton Mowbray landlords who borrowed money to purchase their buy to let property. They have made significantly higher returns than those who paid 100% cash. If the landlord had borrowed 75% of the £70,950 purchase price of the Longfield Road semi-detached house on an interest only 75% mortgage, he would have only needed to invest £17,738 (as his 25% deposit... borrowing the remaining £53,212), but his £17,738 would be worth today, £86,788  (£140,000 less £53,212 interest only mortgage)... a rise of 389.27% - a compound annual return of 11.17%... and I haven’t even mentioned the rent he would have received in those 15 years!

This demonstrates how the Melton Mowbray buy to let market has not only provided very strong returns for average investors since 2000 but how it has permitted a group of motivated buy to let Melton Mowbray landlords to become particularly wealthy. In fact, if this landlord had continued to remortgage the property as it went up in value, he could by our reckoning have had an additional two or three properties (albeit with larger mortgages but greater future potential).


As my article mentioned a few weeks ago, more and more Melton Mowbray people may be giving up on owning their own home and are instead accepting long term renting whilst buy to let lending continues to grow from strength to strength. If you want to know what (and would not) make a decent property to buy in Melton Mowbray for buy to let call me on 01664 569700.

Saturday, May 9, 2015

A stunner on the inside! 5% return

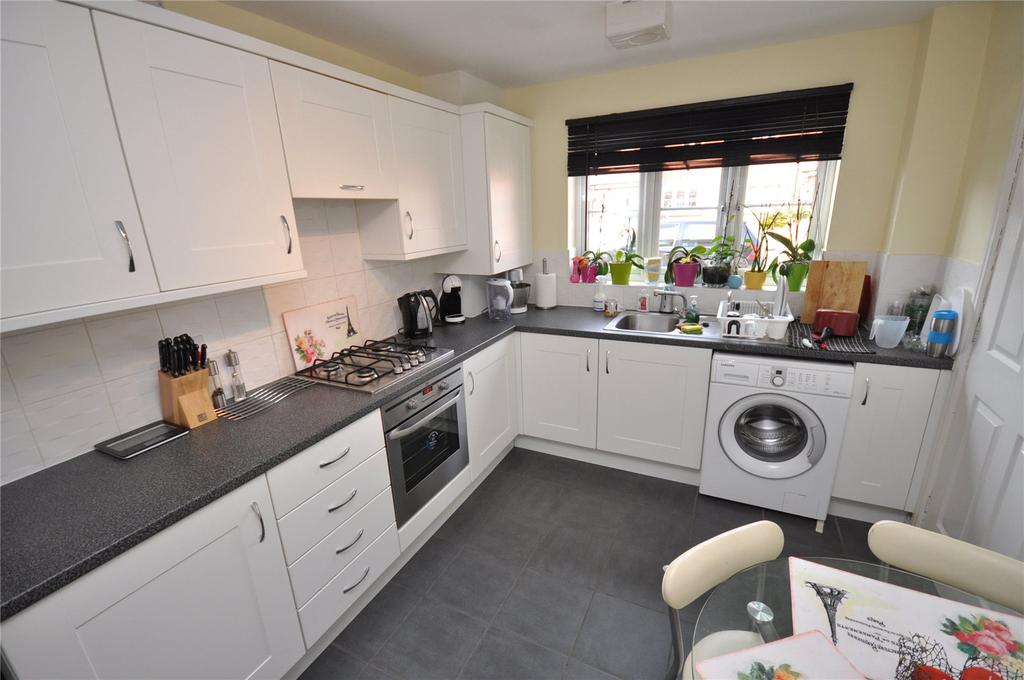
This property is located near to Old Dalby and has been refurbished internally to a great standard. The area has great potential with the talk of new developments and services coming in the future.

This is a great family house with good size rooms. It would easily let for £575 pcm giving a return of 5% if purchased at the asking price.

http://www.rightmove.co.uk/property-for-sale/property-49432969.html


Friday, May 8, 2015

Update - price drop on Wymondham Way Investment!

***********UPDATE - price dropped to £154,950 ******** 
This would let for £650 pcm giving a 5% return.

Previous blog from the 8th April : This 3 bed semi detached property has been extended and is situated in an excellent area. It is for sale with our friends at Harrison Murray for £160,000 and would easily let for £650 pcm. 

The popularity of this area will increase the potential for capital growth on an investment which should be considered along side the potential yield of 4.8% if purchased for the asking price.

Click on the link for more info..

http://www.rightmove.co.uk/property-for-sale/property-48862504.html

Thursday, May 7, 2015

Melton Mowbray Property Market – What is really happening?


I had an interesting conversation with a local Melton Mowbray accountant the other day. He is quite an observant chap (I know this because I have known him for a few years .. but I suppose you have to be to be an accountant!).   Anyway, he mentioned a few things he had noticed recently in Melton Mowbray, one that Melton Mowbray property prices had gone up in the last few years but nowhere near the growth levels that were being achieved in central London, and secondly, that he thought the number of for sale boards in Melton Mowbray (and more importantly ones with sold slips on them) had increased over the last couple of years.

The rate of house price inflation in Melton Mowbray continues to slow with growth of 5.3% in the 12 months to February compared to 7.8% just under six months ago, according to the latest Land Registry data.   However, there is considerable local variation with house price growth ranging from 1.6% in Leicester to 8.3% in Northamptonshire over the last 12 months.

Whilst Melton Mowbray hasn’t seen the 20%+ per year in house price growth of London over the last couple of years, Melton Mowbray has seen a sharp uplift in the number of properties sold throughout  2014 as base line demand for housing grows, which suggests there is substance to the recent pick-up in house price growth in the town.   

Since the Second World War in the UK, when the number of properties sold has grown, property values grew soon after.   The 19.47% uplift in property transactions in Melton Mowbray in 2014, compared to 2013, indicates the most significant recovery in house market activity in Melton Mowbray (outside London) since 2007.

When you compare Melton Mowbray with London, you could be looking at two different countries. In London, its mid/late teens house price to earnings ratios are impacting demand (i.e.  the average property value is often 15 or 17 times the average wage in London .. in fact in Knightsbridge the ratio can be 30 to 1).   Yet the number of people wanting to sell has dropped considerably, meaning that falling sales volumes combined with a general slowdown in activity in the run up to the General Election is resulting in lower mortgage approvals for home purchase.

Transactions are a great indicator for house prices. The acceleration in house price growth in London in the last two years was preceded by three years of rising transactions. A similar pattern is being registered in the Melton Mowbray area, as pent up demand returns to the market supported by low mortgage rates and an improving economic outlook.


But before you get the Champagne out, while the uplift in activity is welcome news, the number of Melton Mowbray property sales in 2014 are still 11.9% lower than the level seen in 2007 and property values are 6.6% below the 2007 levels.   The ongoing housing recovery is far from broad based and remains focused on middle to higher value areas within Melton Mowbray where households have equity and find it easier to access mortgage finance. If you want to know more about the Melton Mowbray Property Market, please visit me at 27 Burton Street, Melton Mowbray or send me an email to charlotte.baker@belvoirlettings.com

Tuesday, May 5, 2015

Kings Road - super location

This three bed semi detached property is for sale with Connells - advertised at £160,000 and is a great house for the area. 

Kings road is known for its Victorian terraces but this property offers off road parking a nice garden and a great layout - very different to a terrace. 

Its a great location for families as it is close to Brownlow Primary School and accesss to the country park. It would let really easily and is in great order, click on the link to look at the floor plan - there is even a utility!

It would let for £625 pcm and this area has seen good capital growth in the last 10 years.


http://www.rightmove.co.uk/property-for-sale/property-51761732.html


Saturday, May 2, 2015

Delightful 2 Bed on Garden Lane - perfect for a buy to let

This 2 bedroom property on Garden Lane in Melton Mowbray needs snapping up by an investor!  It is the perfect buy to let property requiring little / no maintenance (small amount of painting?)  It would let quickly as it is situated in a popular location close to local amenities.

It should see a return of over 5%.

See for yourself here: http://www.rightmove.co.uk/property-for-sale/property-49363150.html


Thursday, April 30, 2015

Two Speed Melton Mowbray Property Market?


Even with the General Election on the horizon, property values in Melton Mowbray are only 0.36% lower than they were 3 months ago, the diversion and ambiguity of an election typically makes house sellers who need to sell, price their property more realistically (although this only lasts a couple of months).

Looking specifically at it from a Melton Mowbray landlord’s point of view, the Melton Mowbray properties favoured by investors are in short supply in many parts of the town because of a number of factors. One of the factors has been that we seen the number of first time buyers increase over the last 12 months in Melton Mowbray.  Another factor has been the fact that the banks have been pushing ‘let to buy’ (yes ‘let to buy’ is different to ’buy to let’) to homeowners (more of ‘let to buy’ in an up and coming article). Next, because of the banks, who are chasing low risk landlords with high deposits with very low mortgage rates- and the low risk landlords with high deposits tend to be attracted to the safer modern two and three bed town houses and semis in Melton Mowbray.

As I mentioned a few weeks back, the pension rules are changing which means buy to let landlords can use some, or all, of their pension pot to buy a property.  It shouldn’t be forgotten there are tax implications taking more than a quarter of your pension pot out (see the article from a couple of weeks ago) , so whilst many pension pots may not be able fund a suitably big enough tax free lump sum to buy the property outright, for most it will provide enough for the 25% deposit (required by most BTL mortgage providers). Remember though the interest paid on the mortgage is tax deductible against the rent, thus lowering your income tax paid.

In the last 12 months, I have noticed a particular uplift in interest from ‘50 something’ Melton Mowbray people wanting to become landlords for the first time. In Melton Mowbray, the highest returns for the lowest investment are at the lower end of the market eg the classic 3 bed semi . Unfortunately 3 bed semis are coming to the market in smaller numbers than the larger four bed’s. 

When looking at the actual numbers, in the later part of the Summer of 2014 in Melton Mowbray, in one month alone 95 three bed properties were on the market in Melton Mowbray. However, in January this year, a notoriously excellent bumper month for properties coming on to the market, there were only 70 three bed properties on the market in Melton Mowbray to choose from. Today, that figure stands at only 61 ..whilst the number of four and five beds has increased significantly ...  interesting don’t you think?

At that lower end of the property market in Melton Mowbray, (ie where first time buyers and landlord investors compete with each other to buy those smaller properties), I believe throughout 2015, there will be a slow and steady tipping of the scales between supply and demand. In fact, from what I am seeing and hearing, early anecdotal evidence has suggested over the last few months (although we will need to look at figures later in the Spring once we have the data from The Land Registry), we are beginning to see a polarised Melton Mowbray property market. We have high demand but low supply at the bottom end of the property market, yet high supply but lower demand at the top of market .. and that can only mean one thing ... prices will go up quicker on the smaller properties than the larger ones in Melton Mowbray, thus narrowing the gap for people looking to move up market!


If you want a chat about the local Melton Mowbray property market, pop in for a coffee or email me on charlotte.baker@belvoirlettings.com 

Friday, April 24, 2015

Modern 3 bed in Asfordby

This modern 3 bed property is located in Asfordby, close to the A6006 which has great links to the A46 Nottingham and Leicester.  The development has okay recently been completed and is very popular with tenants.

The house is being marketed by Connells and should see a rental return of around 5%.

See here for further details:


Thursday, April 23, 2015

Rents Paid By Tenants In Melton Mowbray On The Rise


I was talking to a landlord from Burton Lazars the other day about what is happening to the level of rents that are being achieved in the Melton Mowbray property market.

In terms of rents in Melton Mowbray, it appears that rents being achieved for new rentals (i.e. when the tenant moves out and new tenant moves in) have risen in the order of 3%  in the last 12 months on top of the range modern properties, yet remained static for older Victorian terraced houses and converted apartments.   However, landlords with existing sitting tenants, irrespective of age are not increasing their rents, as most landlords prefer to keep their existing tenant paying the same rent and have the peace of mind that their tenant remains, (thus reducing the risk of a void period).

It must be remembered rents dropped by 7.7%  over 2008/9, due to oversupply in the rental market in 2009.) A lot of the people who couldn’t sell their property in Melton Mowbray in 2008/9 when the Credit Crunch hit in 2008, decided to let their house out to avoid selling at a loss.   In fact, the number of houses on the market in Melton Mowbray dropped by 60.9%  between April 2008 and February 2010, a lot of which came on to the rental market in Melton Mowbray.   However, looking at the longer term, tenants have had it good because since the turn of the Millennium, average wages have grown by 46%.  Rents outside London have only grown by 36% over this period.

I told the landlord that there is a lack of new rental properties in Melton Mowbray coming on the market.   In fact according to the Office of National Statistics, there are only 180 new rental properties coming to the market each year in Melton Mowbray but the population of Melton Mowbray is rising by 240 people per year – something will have to give soon!   This is compounded by the fact a number of landlords are looking to sell their rental properties in the coming months, as the property market in Melton Mowbray has improved.   This is further compounded as tenants in existing rental properties appear to be staying in properties for longer periods of time.

Looking at the rents charged in Melton Mowbray, historic evidence in the UK suggests private market rents have moved in line with general inflation.   Government figures only go back as far as the year 2000, but looking at other countries with similar housing markets (America, Australia, Ireland and Holland) the fact is rents paid by tenants tend to rise in line or just ahead of inflation.

As short term wage growth in Melton Mowbray has eased off recently, rising by only 1.3% in the last 12 months, taking average salaries in Melton Mowbray to £24,921pa.   With the tax breaks announced by The Chancellor in the Budget, I believe, even though rents have kept pace with inflation in the past, renting as an option has become more affordable, and is increasingly seen as a lifestyle choice.   With returning economic growth and expected increases in the rate of growth of wages, above inflation rental growth could rise.


If you want a chat about the local Melton Mowbray property market, pop in for a coffee or email me on charlotte.baker@belvoirlettings.com 

Thursday, April 16, 2015

Melton Landlords invest £328 million in the Melton Property market


East Midlands property asking prices jumped by more than £4,000 to £181,100  in February according to Rightmove, an increase of 2.3% from January and 4.7% higher than a year ago. After the traditionally quiet months of January and February, the property market has started to warm up, but talking to some Melton Estate Agents, they are reporting their lowest ever stocks of quality property for sale. 

However, asking prices have no relation to what property sells for (ie their REAL value), is the issue a lack of supply?

Putting aside Melton’s continual housing supply shortage, (we only built 1,875 properties in the last decade but the population of Melton grew by 2,510), this is now, according to some people, being exaggerated by an increase in homes being owned by buy to let investors, who tend to be buying a property as part of a long term pension plan and are more likely to keep it for longer than an owner occupier would. I have also seen unwillingness among homeowners looking to move, to put their own property on the market as they can find few suitable properties to make it worth their while going through the whole moving process.

Talking to some Melton landlords only last week, I said that I believe this is the new norm in the Melton property market, and is the consequence of over 35 years of not enough homes being built to meet the escalating growth in household numbers, resulting in a lack of quality homes for sale in many popular areas of Melton.

When one looks at the historic data, in April 2008, there were 720 properties on the market in Melton compared to today’s 161. Should we be worried?  Well in February 2010, there were only 281 properties for sale in Melton but ten months later in December 2010, this had jumped to 378 properties, for it to drop to 138 properties in November 2013. The number of properties on the market is a cyclical thing in Melton, it always has been and always will be. As we go into the Spring of 2015, the number of new properties coming onto the market will increase ... just as the daffodils will flower.

So are landlords to blame? Well, on one side of the coin, yes they are. If they buy a property to rent out, that means someone can’t buy it to live in. However, it doesn’t matter if someone wants to live in a property if they can’t afford the deposit and upkeep .. and the youngsters of Melton still need a roof over their head. 

So on the other side of the coin, if the Council aren’t building any properties and people can’t afford the large deposit for the mortgage, then Melton landlords have stepped in and bought property to rent out to them. Melton landlords have bought 1,487 properties over the last decade (investing approximately £328 million buying those Melton rental properties), meaning there were at the last count, 3,054 Melton properties being privately rented out to tenants.

Melton tenants are in fact getting a good deal as well, as average rents in Melton are 4.5%  below where they were seven years ago. That sounds like a win-win situation for everyone to me. Stop blaming landlords and start building more properties in Melton .. that is the only answer.

In the meantime, the demand from Melton tenants for Melton property is only set to rise over the coming years. If you want some advice and opinion on where (or not) to buy, please call me on 01664 569700.

Free Property Investment workshops available in May – email charlotte.baker@belvoirlettings.com for more information.


Wednesday, April 15, 2015

Valiant Way - Nearly new 3 bed

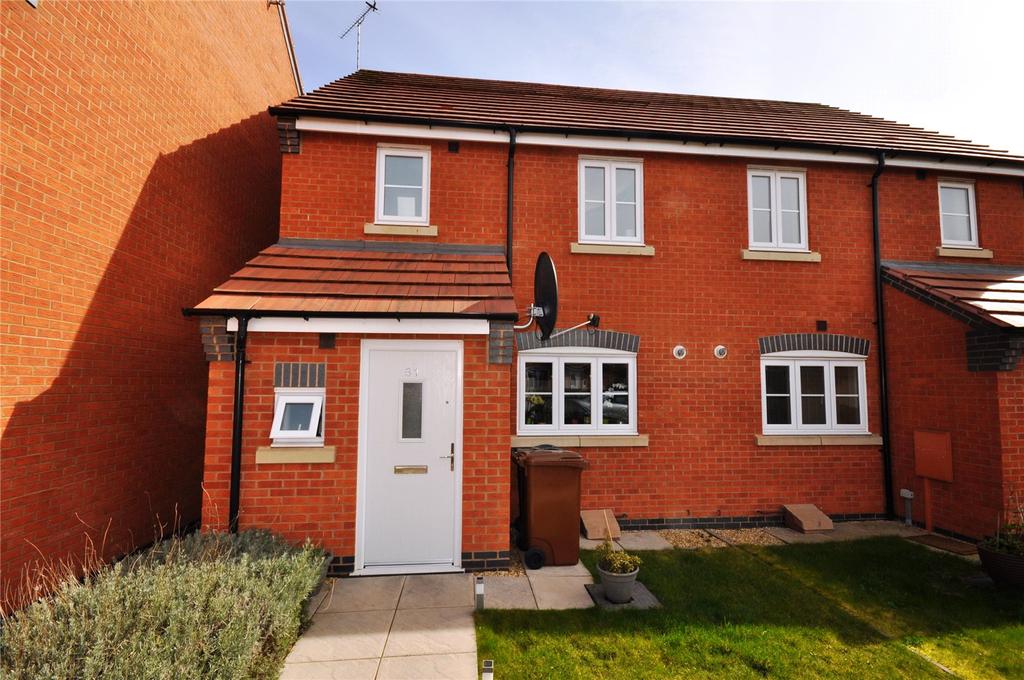
With so few new build developments starting in  Melton this buy might be a good option for those investors looking for a low maintenance investment.

This property would easily let for £595 pcm and tenant demand is really high for modern properties.

Click on the link below for more details..

http://www.rightmove.co.uk/property-for-sale/property-51602741.html


Image 6 of 11: Kitchen

Image 1 of 11: Front

Friday, April 10, 2015

Your Pension could now buy a Buy to Let property in Melton Mowbray


In a recent article, I mentioned that pension rules are changing this April.   It certainly created a few emails, with people asking questions about it.  Therefore, this week, I want to look a little deeper into the subject of your pension and the Melton Mowbray property market.   George Osbourne, in last years’ Budget, announced pension reforms that come into effect this April, which will give people with a pension unprecedented access to their pension pot and the freedom to look for alternatives.   In a nutshell, after the 6th of April, anyone aged over 55 will be allowed to withdraw all or part of their pension pot and spend it as they wish.   Until now, you were allowed to take out a quarter of it and were forced to buy an annuity policy with the rest.

However, my readers always know that I like to tell it ‘as it is’.   There are always two sides to a story, good and bad.   Let me tell you the bad news first.  There are some hefty tax implications by taking money from your pension pot. As before, as per the old rules, the first 25% can still be withdrawn from the pension pot tax free but, here is the sting in the tail, if you take more than a quarter of your pot (25%), anything above that initial 25% level will be taxed as income.   So if you took the whole lot out, the first 25% will be tax free but the remaining 75% will be taxed at your income tax rate of 20%, 40% (or even 45% if you earn over £150,000 a year) .

.. and now the good news!

Under the old scheme, if you bought an annuity, when you died your annuity normally died as well. You would have no asset to pass on to your family.   Also, the returns from pensions are awful at the moment.   The best rates according to Hargreaves and Lansdown (big wigs in the City) state if you were 55 years old, the best rate you would get on your annuity pension would be 4.4% fixed for life (so it would never go up) or 2.2% but the payment would go up with inflation.   The sort of rates (also known as yields in the property investing game) being achieved in Melton Mowbray are in the order of 3.5% to 6.5%.

The other aspect of property investment is how property values have risen consistently over the last 50 years.  According to the Office of National Statistics, the life expectancy of a 65 year old male in Melton Mowbray is 19 years and 4 months (its only 18 years 9 months in Grantham and Stamford).   If we roll the clock back 19 years 4 months to November 1995, property values in Melton Mowbray have risen by 193.7% todate .. you wouldn’t have had that with your pension!   But this is the biggest win, even by taking a hit in income tax now,  by buying a property,  you buy an asset that you can pass on to your family when you die.... (or the cats home if they aren’t nice to you!).

So where next?    It totally depends which strategy you are going to look at, one strategy is to look to achieve relatively small rental returns (i.e. low yields) in an up market area which has decent capital growth or, alternatively, another strategy is to buy properties in not so good areas known to produce a high returns (i.e. high yields) but low capital growth (i.e. how much the value of the property goes up).   Now, I am not financial advisor, so cannot offer financial advice on what the best thing for you with your pension is.   However, I can share my knowledge and experience of the Melton Mowbray property market, what to buy, what not to buy and where to buy etc etc.   


We are holding property investment workshops.  Please register your interest by emailing me on charlotte.baker@belvoirlettings.com or calling 01664 569700.
Wednesday, April 8, 2015

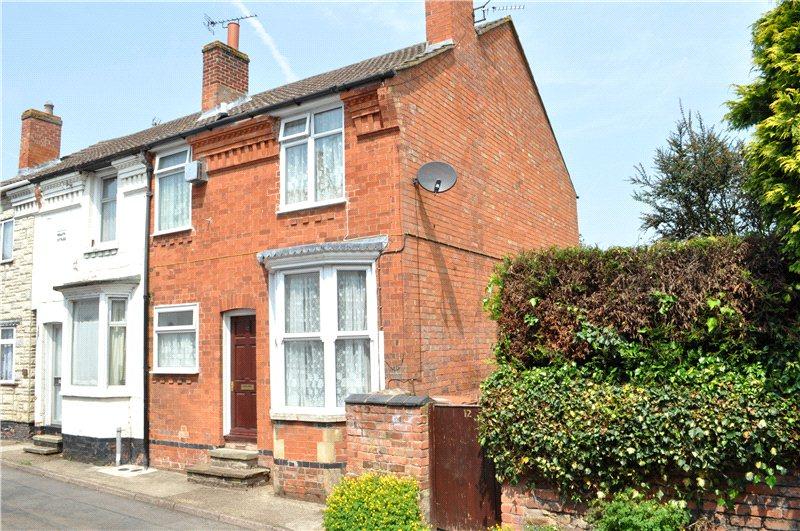
3 bed on Wymondham way - could rent for £650 pcm

This 3 bed semi detached property has been extended and is situated in an excellent area. It is for sale with our friends at Harrison Murray for £160,000 and would easily let for £650 pcm. 

The popularity of this area will increase the potential for capital growth on an investment which should be considered along side the potential yield of 4.8% if purchased for the asking price.

Click on the link for more info..

http://www.rightmove.co.uk/property-for-sale/property-48862504.html


Thursday, April 2, 2015

“The way it works in Melton Mowbray is this, you have to rent where you want to live, or buy where you don’t want to live,”

I had this really interesting chat with some of my tenants the other day on renewal of their tenancy agreement.  They are a lovely couple in their early thirties and I know they have decent jobs in Melton Mowbray.   They have been tenants of ours for quite a while, so I know them quite well.   We got talking and I enquired if they ever thought of buying a property for themselves, to which they replied back with the title of this article.   It made me think and so I did some more research into the subject which I want to share with you.

After the end of the Second World War, just over a quarter of the UK population owned their own home, the rest rented from private landlords or the local Council.  If someone told you in the 1970’s and 1980’s that they rented, they were considered a second class citizen.  Everyone wanted to own their own home ..  it was the done thing.   We think that home ownership will inevitably happen, but it won't.

It all changed in the 1970’s, when two things happened.  Firstly, the number of people who owned their own home broke through the 50% barrier in 1971 and by 1981 it was at 57%.  Tied in with that, the average house prices in Melton Mowbray were doubling at one point every four years in the 1970’s so property and profit started to feed off each other.
To put that growth in context, if we were to look at the last 85 years in Melton Mowbray, in 1930, the average Melton Mowbray property was worth £459.   It took 16 years for Melton Mowbray property values to double, rising to £1,134 by 1946.  Another 15 years and the average Melton Mowbray property doubled again to £2,154 in 1961.  The next doubling only took 10 years, as by 1971 the average Melton Mowbray property had reached £4,380 in value.

It was (as mentioned above) the 1970’s when things really took off, as by 1975 (ie only four years) they had doubled to £9,166 and they doubled again to £18,349 by 1980.  It took another eight years for values to double again, as an average Melton Mowbray property reached £38,380 in 1988. Twelve years had to pass until they doubled again in 2000 (£78,968) and just six years to double again by 2006, when they reached £159,268.  Where are we today?  The average property value in Melton Mowbray currently stands at £220,700.

We could blame Maggie Thatcher for making home ownership the ultimate goal, but what we now need to consider is that the country is turning on its head and we need to, as a Country, love renting again.   Some blame the banks, but obtaining a 95% mortgage is hard work, but nowhere near impossible.   A typical Melton Mowbray first time buyer would only need to save £6,700 for a deposit and fees and they could buy a very decent property.   For example, you could buy a property on the Fairmead Estate in Melton Mowbray, and it would be cheaper each month in mortgage payments than renting.

People might say on the surveys they want to buy, when it comes down to it.  If you have been living in a top of the range large property in Kirby Fields, but the bank will only lend you enough to buy a smaller property on the Fairmead Estate, what would you do?   Don’t get me wrong, the Fairmead Estate has really pulled its socks up over the last ten years, but it isn’t Kirby Fields, is it?  Again, if you were twenty something, what would you do?  Look again at the title of the post ... “The way it works is, you have to rent where you want to live, or buy where you don’t want to live,”

With tenant demand only going in one direction this is probably why more and more people are getting into buy to let in Melton Mowbray.   With the new rules on pensions and the ability to use them to buy residential rental properties from April onwards, this could be the time for you to buy a rental property.   You must take advice on your pension from a Independent Financial Advisor (there are plenty in Melton Mowbray) and you must take advice from people who know what to buy (and what not to buy) in Melton Mowbray to ensure you get the best from your investment.  

If you want a chat about investment properties in Melton Mowbray, then please email me on charlotte.baker@belvoirlettings.com or call 01664 569700


Tuesday, March 31, 2015

Great 2 bed on Wellington Way

Currently for sale with Anthony Hancock, this 2 bed property would make a great investment and should let for £550 pcm. 

It benefits from gas central heating, a modern bathroom with a separate shower cubilcle and a nicely fitted kitchen. 

If the vendor would accept £130,000 then it would provide a 5% return.

Click on the link for full details...

http://www.rightmove.co.uk/property-for-sale/property-49974440.html


Image 3 of 10

Image 8 of 10

Image 1 of 10

Friday, March 27, 2015

Tamar Road, Great looking 2 bed - 5.7% return

Anthony Hancock have this property for sale at £ 119,950 on Tamar Road. It looks like it will need very little work and should let for £575 pcm easily. 

If it was purchased at the asking price it would provide a 5.7% return. This would let easily as the rooms are a good size and it is a great location.

https://www.onthemarket.com/details/1326500/

Image 1 of 8

Image 3 of 8

Thursday, March 26, 2015

Number of Rental Properties in Melton Mowbray set to rise to 4,300 by 2021


I was having an interesting chat the other day with a couple of property investors and the subject of a lack of property for first time buyers came into the conversation.  I wanted to research the Melton Mowbray property market further to investigate our thoughts on the matter. 

At the time of the last census in 2011, 3,401,675 properties in England were privately rented, of which it is estimated, over 1.25 million were owned by private landlords. The rapid growth of buy-to-let is hugely controversial, especially as only ten years before that, there were only 1,798,864 properties under private renting in England. Buy to let landlords have been held responsible for forcing up property prices and preventing our younger generations from being able to buy.

There is also growing resentment toward the billions of pounds in tax relief (estimated to be nearly £10 billion) landlords claim on their mortgage interest -tax relief which is not available to homeowners.They may be asset rich thanks to recently rising property values, but let us not make the landlords the bogeymen they could easily be.  Despite all these benefits enjoyed by private landlords, let us not forget the good they have done, especially in Melton Mowbray.

Property values today in Melton Mowbray are still 6.6%  below the 2007 property boom levels (2007 being the peak of the last property boom before everything dropped in 2008/9), yet inflation has risen by 26% in the same time frame, so in real terms, properties today are 32.6% CHEAPER than they were in 2007.  Just think how low they would be without landlords buying all those rental properties. Interest rates are at an all time low and first time buyers only need to save a £6,700 deposit to secure a lovely 2 bed semi in the Jelson Estate off Leicester Road with a 95% mortgage. Forget what the papers say, first time buyers can borrow money relatively easily on a 95% mortgage and nine times out of ten, it’s cheaper to buy than rent. So why aren’t people buying?

The number of people choosing to rent, either for lifestyle or economic reasons, has grown over the last 15 years. I also believe they will continue to grow for some time to come (as does every report on the subject). In fact I would go as far as to predict the number of rental properties in Melton Mowbray will have risen from the 3,054 properties recorded in 2011 to 4,300 by 2021. Sounds fanciful? Well in 2001, there were only 1,567 privately rented properties in Melton Mowbray.
As a country we are more and more turning into a European model when it comes to home ownership; where the norm is renting for the first ten years; as opposed to the 1960’s to 1990’s, where first time buyers were encouraged to buy as soon as they got a job.


Tenants will also feel the benefit from potential changes in the market. The likelihood of an interest rate increase and existing economic conditions, combined with the uncertainty of new Government manifestos following the General Election in May will result in low demand for people to buy.   This will  also put a dampening effect on increases in rent. As long as landlords buy the right sort of property, which allows for a reasonable yield and decent capital growth, everyone will be a winner. 

If you want a chat about investment properties in Melton Mowbray, then please email me on charlotte.baker@belvoirlettings.com or pop in to see me at 27 Burton Street, Melton Mowbray.

Lovely 2 bed in Asfordby

This lovely property in Asfordby is a good size 2 bed end terrace which has the feel of a cottage. It is being marketed by Bentons at £119,950 and with some modernisation would easily achieve £575 pcm. It is set on a quiet road with on road parking available. 

Click on the link for more pictures ...

http://www.rightmove.co.uk/property-for-sale/property-48612097.html

Image 1 of 11: Picture no. 05

Image 10 of 11: Picture no. 07

Thursday, March 19, 2015

Asfordby – the place to buy a property?


Information is so important when making decisions on what (or not) to buy when investing in Melton Mowbray property. The demand for rental properties is much greater than the supply and in some circumstances, we have four to five prospective tenants for each decent property. 

As always the demand is much greater for properties that are in good areas. Also, we are noticing that tenants are staying longer in their chosen property with some tenants staying four plus years. This is obviously causing problems from the supply of rental property so we are relying on new investment Landlords to bring new properties to the rental market.

 Today, I want to look at the Asfordby to the West of Melton Mowbray. By knowing the different areas of Melton Mowbray, I can weigh up potential hotspots in the rental market and show potential landlords where there could be an opportunity. 

 Looking at the three parts of Asfordby itself; Asfordby Valley had an overall average price of £121,900, whilst Asfordby Hill was slightly higher at £147,000 but the village of Asfordby itself was higher still at £158,400.  As one would expect, the neighbouring village of Frisby on the Wreake was much higher at £273,800.

In Asfordby’s as a whole (ie the Village, Valley and the Hill), there are 3,286 people living in 1,454 properties. It is the home ownership percentages that really got me interested, as it is this information, tied in with our intimate knowledge of the market, where we can match tenant demand to an under supply of rental properties. In Asfordby’s, of those 1,454 households, 74.6%  own their property (compared to the Melton Mowbray average of 72.1%).

There are only 134 rented properties in Asfordby that are in the private rented sector (meaning 9.2% of Asfordby properties are privately rented compared with the Melton Mowbray average of 12.7%). 

The reason the private rental sector is much lower is that Asfordby has a high proportion of homeowners and hardly any local authority housing. The properties do sell well, in fact 252 properties have changed hands since 2007 in Asfordby village, whilst in Asfordby Hill 46 properties have sold since 2007 and 35 in the Valley over the same time frame. However, with such excellent demand from homeowners and tenants, this could be the right area to purchase your next buy to let investment. 


Therefore, if you are considering buying a property for investment in the near future, as I don't sell property, I am always happy to give you my considered opinion on which property to buy (or not as the case may be) to give you what you want from your investment. If you are a landlord, new or old, I am certainly more than happy for you to pick up the phone or visit the Melton Mowbray office on Burton Street.

Perfect for professional couples - an investment property in Rossiter Close, Melton.

This fab 2 bed recently built property is currently for sale with Melton Premier for £139,950.0 

It has a nice garden and parking click on the link for the floor plan..

http://www.rightmove.co.uk/property-for-sale/property-48895783.html

Houses like this suit profession couples and are really in demand in Melton, For that reason we should be able to achieve £625 pcm even though it is a 2 bed - giving a 5.3% return if purchased at the asking price. I could let this a hundred times over!!