Thursday, May 5, 2016

What would Brexit mean to the 8,230 Melton Mowbray Property owners?


If you read all the newspapers, the Brexit debate seems to be focused solely on central London. Many commentators have said Brexit would mean central London would have a lower standing in the world, meaning less people would be employed in Central London, with the implication of lower wages, fewer jobs etc., in Central London ... but we are in Melton Mowbray, not Marylebone, Mayfair or any part of Zone 1 London.

We are home to pork pie, and whilst the central London property market exploded after 2009, that explosion really and honestly didn’t affect the Melton Mowbray property market. So, putting central London aside, what would an ‘in’ or ‘out’ vote really mean for the 8,230 property owners of Melton Mowbray?

Initially, over the coming months, on the run up to referendum, I believe it will be like the run up to last year’s General Election. With the short-term uncertainty in the country, quite often, big decisions are put on ice and people are less likely to make big money purchases i.e. buy a property. However, in the four months up to last year’s Election, property values in Melton Mowbray increased by 2.14%, not bad for a country that thought it would get a hung parliament! So that argument doesn’t hold much weight with me.

Post vote, should the UK opt to leave Brussels, there would be a much more noteworthy impact. I believe that a vote to stay in the EU would see the Melton Mowbray property market return to a status quo very quickly, but the contrasting result could lead to some changes. The principal menace to the Melton Mowbray (and UK) housing market could be variation (in an upwards direction) in interest rates as a result of a Brexit, which could theoretically see the cost of mortgages grow swiftly, pricing many out of the market … but then two thirds of landlords buy without a mortgage, so that won’t affect them.

I suspect whatever decision the electorate of Melton Mowbray and the country as a whole makes, over the long term it won’t have a major effect on the Melton Mowbray property market. We have seen off ‘the end of the world’ credit crunch of 2008/9 and subsequent property crash, the 1988 Nigel Lawson induced post dual-MIRAS property crash, the 1979 Winter of Discontent property crash, the 1974 oil crisis that stimulated another property crash ... hell, we can even go back nearly a century with the 1926 post General Strike slump in property prices...

Today, property prices are 163.96% higher than 21 years ago in Melton Mowbray and are 4.1% higher than 12 months ago. So, make your own decision on 23rd of June 2016 safe in knowledge that whatever the result, there might be some short term volatility in the Melton Mowbray property market, but in the long term (and property investment is a long term strategy) there aren’t enough houses in Melton Mowbray to live in either to buy or rent … and until the Government allow more properties to be built – the Melton Mowbray property market, will be just fine ... even if it has a little blip in the summer, there could be some property bargains on the run up to Christmas to be had!

Keep an eye on this blog for potential property investments and honest rental valuations.

Saturday, April 30, 2016

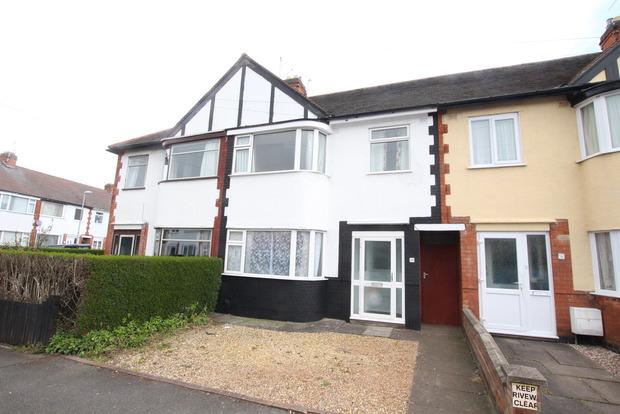
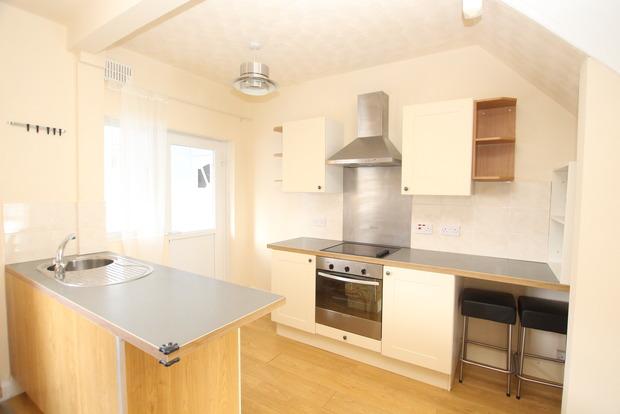
5.5% potential return on Elms Road, Melton Mowbray

This is a really great investment opportunity on Elms Road for sale with Harrison Murray for a shade under £135,000.

It looks a really nice property and would easily let for £625 pcm giving a potential return of 5.5%. Definitely worth a look!

http://www.rightmove.co.uk/property-for-sale/property-59190848.html

Image 1 of 8

Image 2 of 8


Friday, April 29, 2016

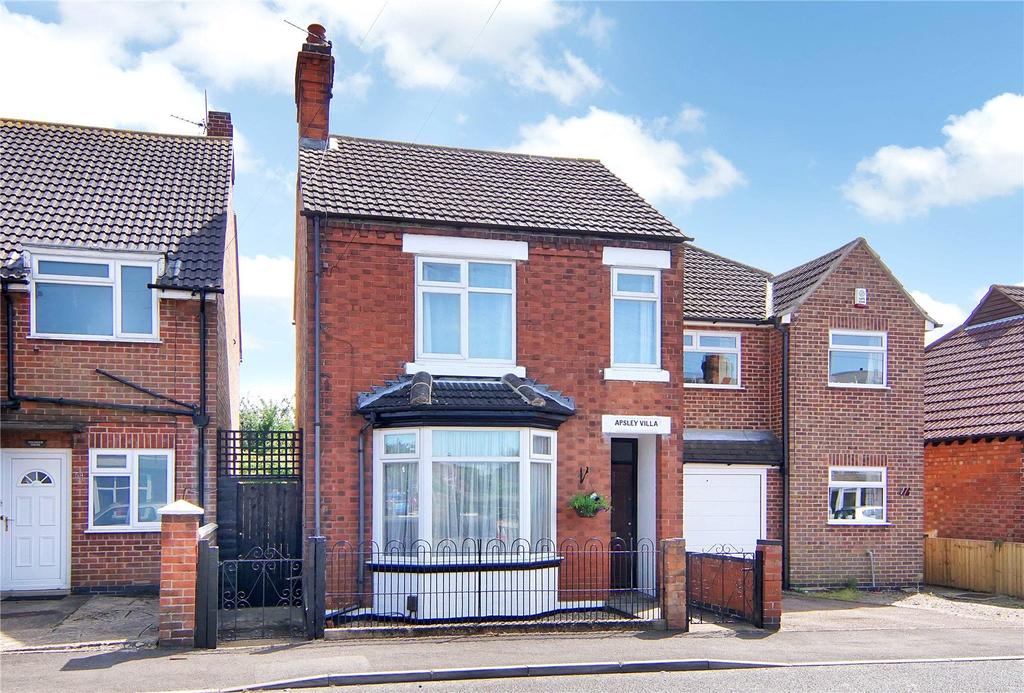
Victorian Villa - Detached property with curb appeal!

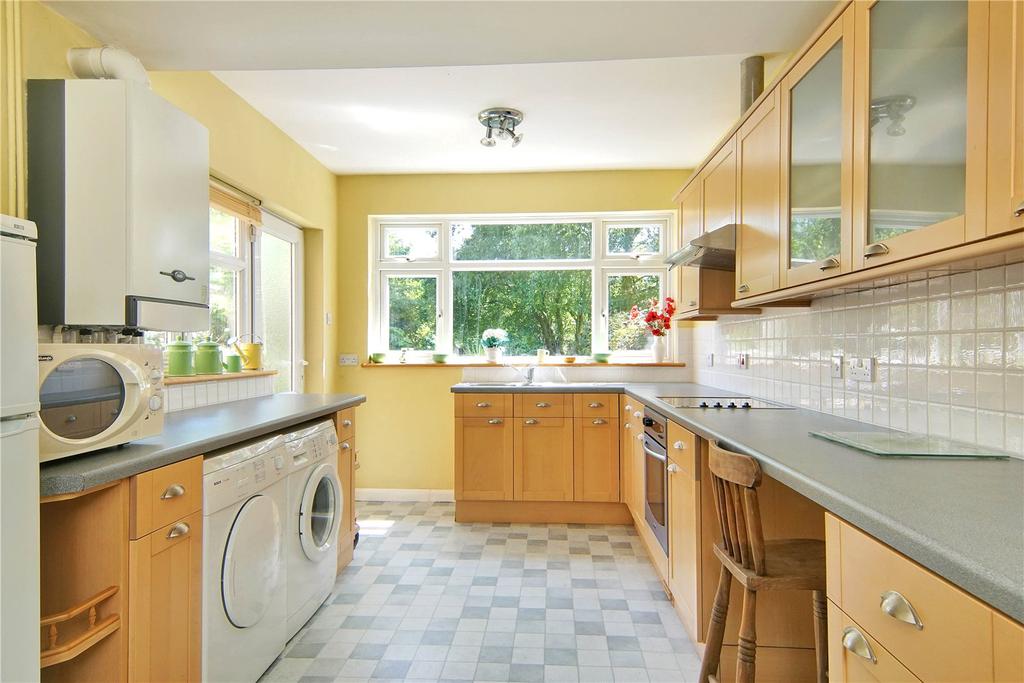
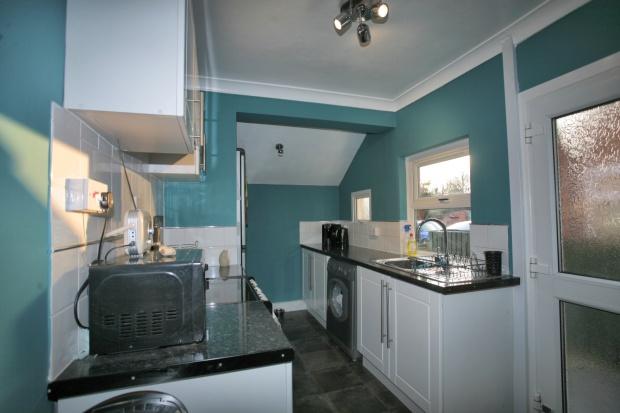
This detached property is on the market with Bentons for a shade under £180,000. Its a detached Victorian Villa, 3 bedrooms with a great garden. It has some of the Victorian features that tenants love and an enclosed rear garden.

It would let really well - even with out parking as it has nice large rooms and I think it would achieve £700 pcm - 4.6% potential return if purchased at the asking price. 

Have a look at the interior below to see why I think it would appeal to tenants...

http://www.rightmove.co.uk/property-for-sale/property-53233997.html

Image 1 of 14: Front

Image 4 of 14: Kitchen

Image 10 of 14: Gardens

Thursday, April 28, 2016

Rents in Melton Mowbray rise by 2.4% in the last year


Last Sunday it was announced UK inflation had increased to its highest level in a year. Inflation, as calculated by the Government’s Consumer Prices Index, rose by 0.3% over the last 12 months.  The report said the rise was due to smaller falls in supermarket and petrol prices than a year ago. If you recall, in early 2015, we had deflation where prices were dropping!

So what does this mean for the Melton Mowbray property market ... especially the tenants?

Back in November, the Office of National Statistics stated average wages only rose by 1.8% year on year, so when adjusted for inflation, Melton Mowbray people are 1.5% better off in ‘real’ terms.   Great news for homeowners, as their mortgage rates are at their lowest ever levels and their spending power is increasing, but the news is not so good for tenants.

The average rent that Melton Mowbray tenants have to pay for their Private Rental Properties in Melton Mowbray (i.e. not housing association or council tenants) rose by 2.4% throughout 2015, eating into most of the growth.  2015 wasn’t a one off either.  In 2014, rents in Melton Mowbray rose by 1.3% (where salaries only rose by only 0.2%) However, it’s not all bad news for Melton Mowbray tenants, because in 2013 rents rose by 1.0%, (but salaries rose by 2.2%).

… and it must be noted that the private rents Melton Mowbray tenants have had to pay for Melton Mowbray property since 2005 are only 15.0% higher, not even keeping up with inflation, which over the same time frame, rose at 27.8% (although salaries were only 22.3% higher over the same time period)

More and more, talking to 20 and 30 somethings who rent – it’s a choice.  Gone are the days where owning your own property was a guaranteed path to wealth, affluence and prosperity.    

We in the UK stand at 64.8% homeownership, in Europe’s powerhouses, only 52.5% of Germans own a home and only 44% of Swiss people are homeowners.  Looks like eating chocolate, sauerkraut, renting and good economic performance go hand in hand.  Yet, joking aside, home ownership has not always been the rule in the UK.   In 1918, only 23% of people were homeowners, with no council housing, meaning in fact, 77% were tenants.

Tenants have choice, flexibility to move, they don’t have massive bills when the boiler blows up, it’s a choice.  Melton Mowbray rents are growing, but not as much as incomes. To buy or not to buy is an enormously difficult decision.   For while buying a Melton Mowbray home is a dream for the majority of the 20 and 30 something’s of Melton Mowbray have, it might not leave them better off in the long run and it isn’t necessarily the best option for everyone.  That is why, demand for renting is only going in one direction – upwards.


Friday, April 22, 2016

Baldocks Lane Melton Mowbray - potential investment £160K

This 3 bed semi is on the market with Newton Fallowell for £159,950 is in great condition and has a garage. 

It would easily let for £650 pcm (being conservative) and is in a popular area for tenants looking for a family property. 

It looks like there is very little to do here to get it ready to let.  

http://www.rightmove.co.uk/property-for-sale/property-53857861.html


Monday, April 18, 2016

Country Park Estate - 3 bed semi, investment potential

This 3 bed semi on Old Bridewell - the desirable Country Park Estate - is on the market with Harrison Murray for £159,950. It needs updating inside but with the garage and the nice plot it could let for around £650 pcm.

Definitely worth considering as capital growth levels are good on this estate.

http://www.rightmove.co.uk/property-for-sale/property-58925186.html

Image 1 of 8

Image 5 of 8

Friday, April 15, 2016

Richard Close - low maintenance potential investment property


This property on Richard Close, just off Saxby Road, is on the market for sale with Melton Premier for offers over £145,000. 

Its a lovely 2 bed which would let really easily, whilst the yield may not be as impressive as an ex-authority property it would have few voids and would require little maintenance.

http://www.rightmove.co.uk/property-for-sale/property-58715471.html


Thursday, April 14, 2016

Reports of the death of 'buy to let' for Melton Mowbray have been greatly exaggerated


Some commentators are saying buy to let is about to die, with the new stamp duty changes and how mortgage tax relief will be calculated.   Some say 500,000 rental properties will flood the market nationally in the next 12 months as landlords leave the rental market.   Have you heard the phrase ‘Bad news sells newspapers’?   Let me explain why buy to let in Melton Mowbray is only going in one direction – and not the direction the papers say they are going.

According to Sheffield University, buy to let landlords will continue fuelling the growth of the private rented sector in the coming decades.   By their estimates (and they are considered a centre of excellence on the topic), the rate of homeownership nationally will fall to 50% (today it is 72% in Melton Mowbray) by 2032, while the rate of private sector renting will increase to 35% (interestingly, in Melton Mowbray it stands at 13.2% today).

Therefore, the demand for rental accommodation in Melton Mowbray will grow by 314 households in the next five years ... and these are the reasons why, irrespective of the distractions set out in the newspapers.
         
Melton Mowbray property values over the last six years have risen a lot more than average wages/salaries, meaning as homeownership and mortgage availability is dependent on your ability to pay has served to push home ownership further out of reach for many, at a time when the stock of council houses has actually withered.   (Nationally, the number of council houses in the last ten years has dropped from 3.16m to 2.18m households - a drop of 31.1%).

Now it’s true that the Government’s efforts to fix the deficiency of affordable housing has focused on those who want to buy a home, ranging from Help to Buy and Starter Home Schemes, an initiative offering a 20% discount for first time buyers … but if you are unable to save for the deposit ... none of this means anything to the ‘20 something’s’ of Melton Mowbray ... and they still need a roof over their heads!

This prediction in growth of the Melton Mowbray rental market is even on the back of the government clamping down on tax reliefs for landlords.   The point is this, gone are the days of making guaranteed returns on BTL property.   For the last 20 to 30 years, irrespective of which property was bought, making decent money on buy to let property was like shooting fish in a barrel – anyone could do it  - but not now.   Landlord’s must take a more considered approach to their existing and future portfolio, especially in Melton Mowbray.   The balance of capital growth and yield, especially in this low interest rate world we live in, means Melton Mowbray landlords need to do more homework to ensure the investment in property gives the desired returns.   

Thursday, April 7, 2016

Winster Crescent potential investment property

This nice 3 bed semi is on the market with Melton Premier at £154,950 and as it has a garage I am confidant it would let for at least £600 pcm. 

With nothing needed to be done in the property to get it ready to let this could see a 4.6% return if purchased for the asking price. 

http://www.rightmove.co.uk/property-for-sale/property-40330626.html


2.0% rise in Melton Mowbray Property Values adds weight to the town’s Housing Crisis


Melton Mowbray’s continuing housing shortage is putting the town’s (and the Country’s) repute as a nation of homeowners ‘under threat’, as the number of houses being built continues to be woefully inadequate in meeting the ever demanding needs of the growing population in the town. It used to be that if you went out to work and did the right thing, you would expect that relatively quickly over the course of your career you would be buying a house, you would go on holiday every year, you would save for a pension.   But now things seem to have changed?

Back in the Autumn, George Osborne, used the Autumn Statement to double the housing budget to £2bn a year from April 2018 in an attempt to increase supply and deliver 100,000 new homes each year until 2020.  The Chancellor also introduced a series of initiatives to help get first time buyers on the housing ladder, including the contentious Help to Buy Scheme and extending Right to Buy from not just Council tenants, but to Housing Association tenants as well.

Now that does all sound rather good, but the Country is only building 137,490 properties a year (split down 114,250 built by private builders, 21,560 built by Housing Associations and and a paltry 1,680 council houses).    If you look at the graph (courtesy of ONS), you will see nationally, the last time the country was building 230,000 houses a year was in the 1960’s.


How George is going to almost double house building overnight, I don’t know, 

Looking at the Melton Mowbray house building figures, in the local authority area as a whole, only 70 properties were built in the last 12 months, all of them were privately built properties with none built by housing associations and not one council house being built.   This is simply not enough and the shortage of supply has meant Melton Mowbray property values have continued to rise, meaning they are 2.0% higher than 12 months ago, rising 1.6% in the last month alone.

It’s all about supply and demand, this economics game.   The demand for Melton Mowbray property has been particularly strong for properties in the good areas of the town and it is my considered opinion that it is likely to continue this year, driven by growing demand among buyers (both Melton Mowbray homebuyers and Melton Mowbray landlords alike). You see Melton Mowbray’s economy is quite varied, meaning activity is expected to remain relatively strong into the early Summer of 2016..

.. and of supply, well we have spoken about the lack of new building in the town holding things back, but there is another issue relating to supply.   Of the existing properties already built, the concern is the number of properties on the market and for sale.   The number of properties for sale last month in Melton Mowbray was 122, whilst 12 months ago, that figure was 168, whilst three years ago it stood at 217… a massive drop!

With demand for Melton Mowbray property rising, minimal new homes being built and less properties coming onto the market, that can only mean one thing ... now is a good time to be a homeowner or landlord in Melton Mowbray.   

Thursday, March 31, 2016

Has owning a home become an unattainable dream for the 333 Melton Mowbray 28 year olds


My parents bought their first house in the 1970’s, they were in their early 20’s. Interestingly, looking at some research by the Post Office from a few years ago, in the 1960’s the average age people bought their first house was 23. By the early 1970s, it had reached 27, rising to 28 in the early 1980’s.

This year alone, 333 people in Melton Mowbray will turn 28 and 315 in 2017 .. and dare I say 361 in 2018 .... where are the Melton Mowbray youngsters going to live?

Ask a Melton Mowbray ‘twenty something’ and they will say they do not expect to buy until they are in their mid thirties - seven years later than the 1980’s. One of the major problems facing young Melton Mowbray people is the large deposit needed to get a mortgage .. or is it?

The average price paid for an apartment in Melton Mowbray over the last 12 months has been £115,600 meaning our first time buyer would need to save £5,780 as a deposit (as 95% mortgages have been available to first time buyers since 2010) plus a couple of thousand for solicitors and survey costs. A lot of money, but people don’t think anything today of spending a couple of thousand pounds to go on holiday.

I was reading a report/survey commissioned by Paragon Mortgages from the autumn of last year. The thing that struck me was that when tenants were asked about their long term housing plans, some 35% of participating tenants intend to remain within the rental sector and 24% intended to buy a house in the future, with the proportion of respondents citing the “unaffordability” of housing as the reason for renting privately increasing from 69% to 74%.

However, time and time again, in the starter home category of property, nine times out of ten the mortgage payments to buy a Melton Mowbray property are cheaper than having to rent in Melton Mowbray. It is the tenant’s perception that they believe they can’t buy, so choose not to.

Over the last decade, culturally in the UK, there has been a change in the attitude to renting so, unless that attitude changes, I expect that the private rental sector in Melton Mowbray (and the UK as a whole) is likely to remain a popular choice for the next twenty plus years.

With demand for Melton Mowbray rental property unlikely to slow and newly formed households continuing to choose the rental market instead of purchasing a property. I recommend landlords pursue professional advice and adopt a realistic approach to rental increases to ensure that they are in line with inflation and any void periods are curtailed. 


Saturday, March 26, 2016

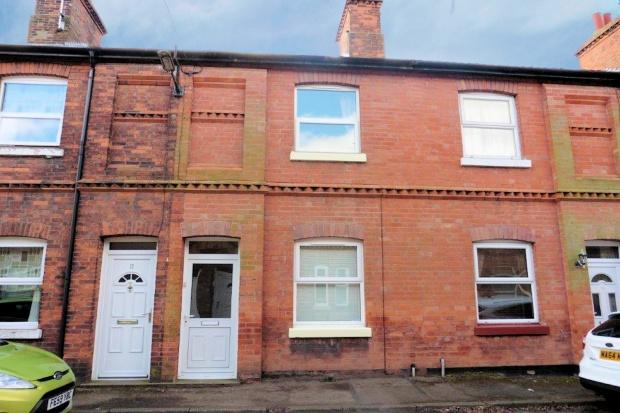
£120,000 for a great 2 bed terrace, potential 5.7% return


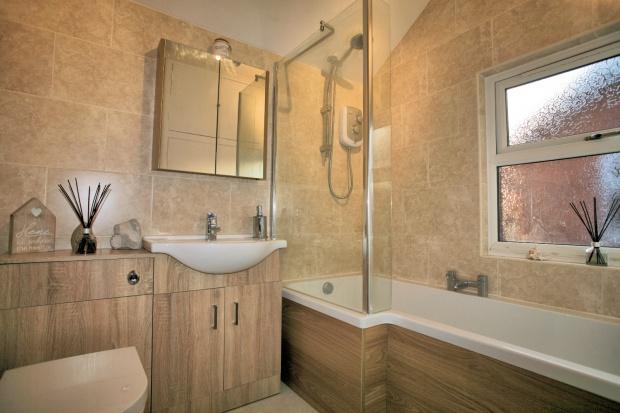
This property is for sale with Harrison Murray and is listed as offers over £119,950. It is a lovely example of a 2 bed terrace and has a separate shower cubicle in the bathroom.

It would easily achieve £550 pcm, they have gone for £575 pcm on this street recently. It could see 5.7% return

http://www.rightmove.co.uk/property-for-sale/property-54340499.html

Image 1 of 7

Image 6 of 7

Image 2 of 7

Friday, March 25, 2016

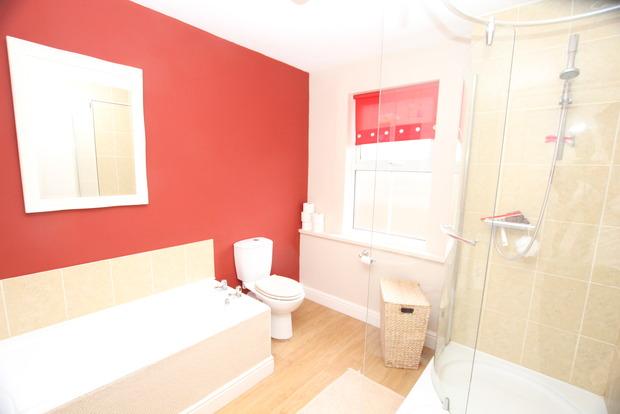
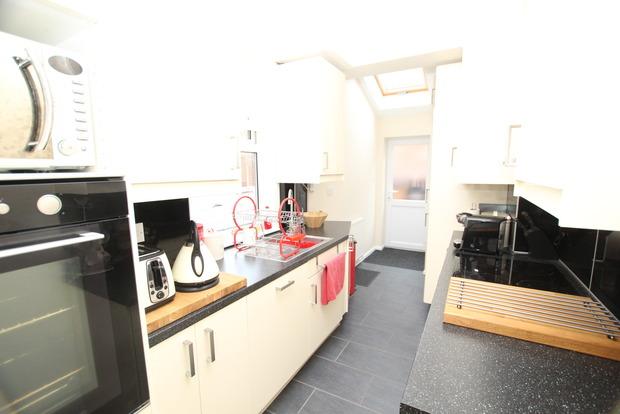
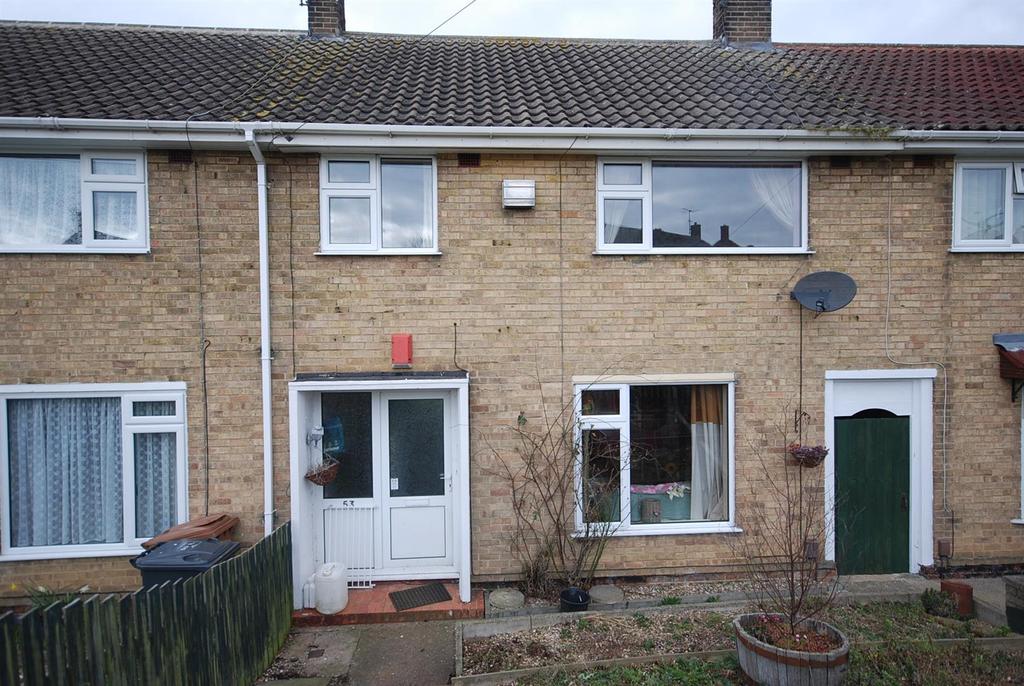
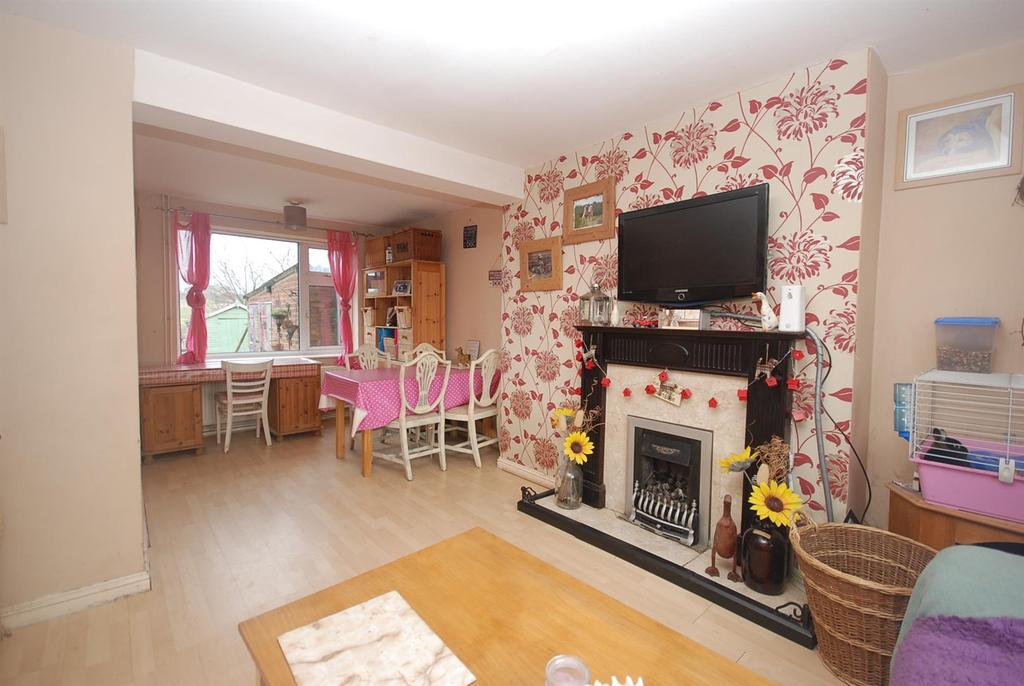
Ex Authority property offering 6% return

This 3 bed is on the market for £ 109,950 with Richard Watkinson on West Avenue in Melton Mowbray.

The details state the property is in need of upgrading however it is a large three bedroom property and although it is ex-authority it is the type of property that would provide an investor a good yield. 

I am always cautious when it comes to investing in ex-authority properties (see my article on the blog yesterday - 24th March) however this street has always let well as it backs onto the Defence Animal Centre horse paddocks. 

3 bed properties like this can go for £600 pcm + if they are in good order so even if £10,000 was spent on the property it could see a potential yield of 6%

http://www.rightmove.co.uk/property-for-sale/property-58446389.html


Image 1 of 7: Dsc 1584.jpg

Image 3 of 7: Dsc 1576.jpg


Image 5 of 7: Dsc 1579.jpg

Thursday, March 24, 2016

Only 1,814 Council Houses in the Melton Mowbray area left – opportunity or problem?


The ‘Right to Buy’ scheme was a policy introduced in 1980 which gave secure council tenants the legal right to buy the Council home they were living in with huge discounts. The heyday of Council ‘Right To Buys’ was in the 80’s and 90’s, when 1,719,368 homes in the country were sold in this manner between October 1980 and April 1998. However, in 1997, the discount available to tenants of council houses was reduced and the numbers of properties being bought under the Right to Buy declined.

So what does this mean for Melton Mowbray homeowners and landlords? Well quite a lot in fact!

Looking at the figures for our local authority, whilst the number of ‘Right to Buys’ have dwindled over the last few years to an average of only 7 ‘Right to Buy’ sales per year, one must look further back in time. Looking at the overall figures, 1,301 Council properties were bought by council tenants in the Melton Borough Council area between 1980 and 1998. Big numbers by any measure and even more important to the whole Melton Mowbray property market (i.e. every Melton Mowbray homeowner, Melton Mowbray landlord and even Melton Mowbray aspiring first time buyers) when you consider these 1,301 properties make up a colossal 8.4% of all the privately owned properties in our area (because in the local authority area, there are only 15,498 privately owned properties).

Melton Mowbray first time buyers and landlords can now buy these ex-council properties as those original 80’s and 90’s tenants (now homeowners) have more than passed the time of any claw back of the discount they received.

Now let us all be honest, some (not all), but some ex-council properties lack the vital Kerb appeal that some landlords crave.

Yes, the modern stuff being built in Melton Mowbray is lovely, but too many landlords purchase buy to let property solely based on where they would choose to live themselves, instead of choosing with a business head and choosing where a tenant would want to live ... because remember the first rule of buy to let property … you aren’t going to live the property yourself. What an ex-council property lack in terms of kerb appeal, they more than make up for in other ways.  Tenants more worried about how close the property is to a particular school or family members, or the size of the rooms matter to them far more than the look of a property.

Whilst ex-council properties tend to increase in value at a slower rate than more modern properties, that is more than made up in the much higher yields – and those built between the wars or just after are really well built. Tenant demand for such properties is good since Melton Mowbray property values are so expensive, a lot of people can’t get mortgages to buy, so they will reconcile themselves to renting, meaning there is a good demand for that sort of property to rent. Also, the very fact the council were forced to sell these Melton Mowbray properties in the 80’s and 90’s, means that today’s younger generation who would have normally got a council house to live in themselves, now can’t as many were sold ten or twenty years ago.

So to Melton Mowbray landlords I say this … don’t dismiss ex-council houses but remember the 1st rule of buy to let (see above). However, those very same Melton Mowbray landlords should go in with their eyes open and take lots of advice. Not all ex-council properties are the same and even though they have good demand and high yields, they can also give you other headaches and issues when it comes to the running of the rental property. 

2 bed investment property should see a 5.59% return


This really well presented property is on South Street in Asfordby Hill and for sale with Middletons for £118.000. 

We have one a few doors away that has recently let for £550 pcm and if purchased for the asking price would see a return of at least 5.59%. 

http://www.rightmove.co.uk/property-for-sale/property-58412111.html

Image 1 of 10

Image 7 of 10

Image 4 of 10

Friday, March 18, 2016

Rosebery Avenue - Just reduced to offers over £120,000


This 3 bed is up for sale with Connells and is listed as offers over £120,000. It is on Rosebery Avenue and we let a few around there.

It would easily let for £550 pcm which would give a potential return of 5.5% if purchased for £120,000. The property looks to be in good condition and has a garden that could be quite appealing with a little work. Definitely one to consider...

http://www.rightmove.co.uk/property-for-sale/property-58096583.html


Thursday, March 17, 2016

999 Melton Mowbray Homes bought by private landlords in the last 20 years – Is this the end for first time buyers?


I had a chat with a local landlord and he wanted to know my thoughts on the future of the Melton Mowbray property market. People are always going to need a roof over their heads and somewhere to live will never go out of fashion – it’s a necessity for every single person.

The 22 to 30 year olds of the town have a choice to what type of roof they have ... they rent from the Council, they can rent from a private landlord or finally they can get a mortgage and buy one. In the 1970’s/80’s and 90’s, the expected thing was to save like mad for two years for the deposit (going without luxuries) whilst living at home or renting a cheap two up two down, then buy your first house. More recently fewer Melton Mowbray youngsters have been buying, choosing to rent instead – mainly from private landlords (as Councils have been selling off council housing on the Right to Buy Schemes). The numbers are truly staggering ... and I want to share them with you.

Roll the clock back 20 years and Melton Mowbray was a different place. There were 9,763 households in Melton Mowbray and 7,224 of those were owner occupied. Move to the present, and with all the building in the town, the total number of households has increased by 18.95% to 11,613 and quite surprising (to me at least), the number of owner-occupiers has increased to 8,237 (although as a proportion, it is only 70.9% compared to 73.9% twenty years ago).

However, it’s rented sector that is truly fascinating … twenty years ago, only 534 properties were privately rented in Melton Mowbray ... and now its 1,533, a rise of 999.

The twentysomethings of Melton Mowbray housing difficulties haven’t been helped by the local authority selling off council housing, with the number of council houses dropping from 1,364 to 1,176 over the same twenty-year period. Demand for decent rented property remains high, as Cameron’s much vaunted house building program is years away and has decades of under investment to catch up on before it starts to affect demand.

Even with the Buy to Let tax rule changes over the coming few years (which will see the maximum tax relief available to landlords drop from 45% to 20%), private landlords still have an important role to play in housing the people of Melton Mowbray and those who educate themselves and treat it as a business will survive and prosper.

The best way Melton Mowbray landlords can protect their income from property (and mitigate the affects of the tax rises) is to keep the homes they let out in Grade A condition. I have found, especially over the last three or four years, Melton Mowbray tenants have ever growing demands from their rental property, but many are prepared to pay ‘top dollar‘ for houses and apartments that meet their high expectations. You must not forget, letting property in Melton Mowbray (in fact anywhere) is a business, so all private landlords should also seek the advice, opinion and commentary of property professionals.

He also asked ‘What of the news of Stamp Duty changes for Landlords coming in April?’ My thoughts are with such low supply (i.e. numbers of property for sale), and high demand it is hard to imagine Melton Mowbray property values will see much impact – but I predict, ever so slightly, the proportion of owner occupiers should increase slightly compared to buy to let landlords in the coming decade as the the housing market should return to balance. For more in-depth thoughts on the Melton Mowbray Property Market, please feel free to give me a call on 01664 569700.

Thursday, March 10, 2016

Private Renting in Melton Mowbray increases by 100.84% in 20 years


 George Osborne has decided now is the time to change taxation for buy to let property, many pundits are predicting the end of buy to let as we know it. However, it is still possible to make a reasonable, profitable and safe return on property with these changes.

You need to study the market, take advice and opinions from many people and then decide what the best course of action should be… remember, tenants will always want a roof over their head and I don’t see the HM Government building the millions of houses required to house them?

Looking specifically at the Rutland and Melton Parliamentary Constituency, twenty years ago, 24,218 households (meaning 68.37% of property) was owned and only 2,513 households were privately rented (meaning 7.09% of property was rented out by private landlords). Roll the clocks on twenty years and 30,376 of properties in the Constituency are home-owners (72.52% being owner occupied) and the jump in private renting has high, as 5,968 properties are now privately rented proportionally 14.24%). (NB Neighbouring Constituencies show similar changes as well).

Who would have predicted in 1995 the private rental sector in
Melton Mowbray would have grown by 100.84% in the proceeding 20 years?

Also, if you had asked someone in 1995 to predict what would happen to property values over the proceeding 20 years (ie between 1995 and 2015), they might have predicted similar growth to the growth experienced over the previous 20 years (ie between 1975 and 1995), which was a very impressive 351.55%. Yes, property values in Melton Mowbray have increased over the last 20 years (between 1995 and 2015), but by a more modest 163.29% (and most of that can be attributed to house price growth between 2000 and 2006.)

The property market is constantly changing and buy to let for too long has been heavily dependent solely on house price growth, where yield has been almost forgotten.  I see the changes in tax and landlord and tenant law in a different perspective to the doom-mongers and see it as bringing many opportunities.

You might need to change your buy to let benchmarks, your approach to financing or even consider places other than Melton Mowbray in which to invest your money, but this will shine a light on investing in properties with healthier yields and create more realistic long term buy to let opportunities, instead of short term growth bets and wagers.

The advice I give to my landlords is these changes will make some landlords panic, meaning competition for decent Melton Mowbray buy to let bargains will reduce as fear of change kicks in and amateur investors leave the market. These opportunities will provide a more stable platform for knowledgeable and wise Melton Mowbray buy to let landlords to thrive in.
If you want to learn more about the Melton Mowbray Property Market, feel free to pop in for a coffee at our office for a chat with me at 27 Burton Street.

Monday, March 7, 2016

Baldocks Lane - Capital growth and a reasonable yeild

This property is listed with Anthony Hancock and is on Baldocks lane for sale at £159,950. 

It is the type of property which would easily achieve £625 pcm (potential 4.8% yield) and should see a good level of capital growth as it has room for extension in the future. This is something that will really help when it comes to re sale. 

https://www.onthemarket.com/details/2522840/

Image 1 of 12

Image 3 of 12


Thursday, March 3, 2016

£145,000 inheritance - Is buying Melton Mowbray Property still the best place for my windfall?


I had an interesting email from a gentleman recently that I want to share with you (don’t worry he is happy that I share this with you all). In a nutshell, he lives in Asfordby, still works and is in his mid 60’s.  He has a decent pension, so that when he does retire in a couple of years’ time, it will give him a comfortable life.

He recently inherited £145,000 from an elderly aunt and was looking at options on how best to invest this.  One option he said was to put it into a savings account or a 2 year bond with the Post Office, this paid 1.9%; meaning he would get £2,755 in interest a year.  His other thought was to buy a property in Melton Mowbray to rent out and he wanted to know my thoughts on what he should buy.   He didn’t want to take a mortgage out at his time of life and was also worried about all the tax changes he had read about in the papers for Landlords.

Notwithstanding the war on Melton Mowbray landlords being waged by George Osborne, the attraction of bricks and mortar endures for many.  As our man is a cash buyer, he would not have to deal with the intricate cut to mortgage interest tax relief that will diminish, or even eradicate, the profits of many Melton Mowbray landlords.  It’s true he would face the extra 3% in stamp duty to buy a second property, but with some good negotiation techniques, that could soon be mitigated.

I told him that buying a Melton Mowbray buy to let property is all about the total return on investment.  Yes, he could put the money in the Post Office bond and receive his interest of £2,755 a year or, as he rightly suggested, invest in property in Melton Mowbray.  The average yield (yield being the equivalent of the interest rate on the property) at the moment in Melton Mowbray is 3.95% per annum, meaning our potential F.T.L (First Time Landlord) should be able to, depending on what he bought in the town, earn (before costs) £5,727 a year.

The bottom line is that the success of investing in Melton Mowbray buy to let property versus a savings account with the Post Office, Bank or Building Society offering the best rate) will depend on the performance of those assets.  Unlike with a savings account, with property the capital you invested can also go up (and yes, it can go down as well – more of that in second).  Property values in Melton Mowbray have risen in the last twelve months by 3.2% meaning, that if our chap had bought a year ago, not only would he have received the £5,727 in rent, but also seen an uplift of £4,640 … meaning his overall return for the year would have been £10,367 (not bad when compared to the alternative saving options!).

Some of you will say, property values can go down, as they did in 2008, and in 1988 and 1979.  This is true, but after 1979 prices had bounced back to their ’79 levels by 1984 they went on to grow an additional 58% in the following four years.  In 1988 they dropped and did take 13 years to reach back to those ’88 figures, but the following six years (between 2001 and 2007) they then increased by an additional 66%.   According to the Land Registry, average property values in Leicestershire currently stand 3.46% below the January 2008 level, and anecdotal evidence suggests that in the nicer parts of Melton Mowbray, we are well above these sorts of levels.  Therefore, all this talk of property crashes is unfounded.


So, what would that £145,000 get you in Melton Mowbray?   A decent 3 bed semi in Asfordby or close to the Melton town centre, maybe a 2 bed semi off Nottingham Road .. in fact, the world is your oyster.   But which Oyster?   If you want to read similar articles like this and what I consider to be the very best of buy to let deals in Melton Mowbray, irrespective of which agent is selling it, then follow this blog.