Thursday, January 28, 2016

Melton Mowbray Landlords count the cost of a Conservative Election win


Can you remember 10.05pm on Thursday, 7th May 2015 ... with the shock news that BBC Exit Polls suggested the Conservatives would be returned with majority? Melton Mowbray landlords had something to cheer about as the Conservatives were always considered to be a political party that accepted the importance of the rental market, supported its development while properly targeting the lawbreaker landlords renting out below standard rental accommodation.

Since May though, George Osborne announced future rises in stamp duty for buy to let landlords and a change in the interest relief on buy to let mortgages, some people have started to question that loyalty.

I will admit the loss of mortgage higher rate tax relief will make a number of properties not stack up financially. The new rules are likely to slow demand in the Melton Mowbray housing market, which is in fact good news for the other landlords, as there is less competition from other rental properties available to let.  

Just a thought, but making Melton Mowbray landlords think twice and
run their numbers more cautiously is not such a bad thing.

Over the last 12 months, property values in Melton Mowbray have risen by 3.2%, not bad when you consider inflation is running at -0.1%.

The really interesting information is the value growth, but what types of property are actually selling in Melton Mowbray?  Looking at all the properties sold, as recorded by the Land Registry, within 2 miles of the centre of Melton Mowbray in September 2015 (this data always runs a couple of months behind the house price data) compared to September 2007 (a couple of months before the credit crunch started to bite and the subsequent property crash).


Sept 2007
Sept 2015
Difference
Detached in Melton Mowbray
14
19
+36%
Semis in Melton Mowbray
17
18
+6%
Terraced Houses in Melton Mowbray
12
14
+17%
Apartments / Flats in Melton Mowbray
5
4
-20%

Now I have mentioned in previous articles that the numbers of properties selling in the town has certainly dropped post 2008, but what amazed me were the drop in the number of apartments selling in Melton Mowbray compared to the rise in sales of detached, semis and terraced properties.

Less properties are selling than last decade in Melton Mowbray
and the types of properties selling have changed ...
interesting times ahead for the Melton Mowbray Property market!


Therefore, all I can say to the landlords of Melton Mowbray is do your homework, make sure the numbers do stack up, take advice and opinion from professionals and above all, for those of you planning to add to your portfolio, buy the right property at the right price. Please do not hesitate to give me a call or pop into our office on Burton Street.

Wednesday, January 27, 2016

Kings Road - smart 2 bed - 5.1% return

This well presented 2 bed terrace, around the corner from the Algernon road one, has come onto the market with Newton Fallowell. It is listed at a shade under £135,000 and should let for £575 pcm. 
If purchased at the asking price it could produce a 5.1% return for an investor. 

It looks to need very little work and has great curb appeal and an easy to maintain garden. 

http://www.rightmove.co.uk/property-for-sale/property-57486449.html


Monday, January 25, 2016

Algernon Road £120,000 - minimum 5.2% return

Offering a good entry to buy to let investment this 2 bed terrace is on the market for sale at £120,000. It would let for a minimum of £525 pcm which would give a potential return of 5.2%. 

If its as nice inside as the pictures look then we would hope to get nearer £550 pcm.

This is a popular area for tenants and with this kitchen and bathroom it would let really quickly. 


http://www.zoopla.co.uk/for-sale/details/39276356


Thursday, January 21, 2016

Melton Mowbray Landlords could be fined £33,000 per year


On a cold wet evening last week I met a landlord who had been self-managing his buy to let property over the last few years. He was worried with all the new legislation that had been introduced recently. He was particularly concerned about the up and coming ‘Right to Rent’ legislation, so as his tenant had handed in their notice recently, on this new tenancy he called us for our opinion.

Landlords will need to check the immigration status of any new tenants moving into properties from February 2016 or face a £3,000 fine. It is called the 'Right to Rent' rules. However, tenants should also be aware that as well as traditional landlords, tenants who sub let rooms and homeowners who take in lodgers, must also check the right of prospective tenants to reside in the UK.

He wanted to know how much of a real issue was ‘Right to Rent’ in Melton Mowbray. I was able to tell him, the last available figures (from a couple of years ago) show that 11 people (whom were registered as Non-UK Born Short-term Residents) moved into private rented accommodation in the Melton District Council area in one year alone. If all of those people weren’t supposed to be in the UK, that would be a fine of £33,000 to the landlords of the town.

It must also be recognised that landlords, by checking up on tenants, could potentially be accused of discrimination under the Equality Act. This is a real minefield for landlords, especially when you consider that not all of the 1,028 Europeans in the area necessarily have the right to live in the UK either.

In a nutshell, Melton Mowbray landlords will need to check and retain copies of certain documents that show a potential tenant has the right to live in the UK. These include ....
·         UK Passport
·         EEA Passport/Identity card
·         Travel document or Permanent Residence Card showing indefinite leave to remain
·         Paperwork from Home Office stating their Immigration status
·         Certificate of registration or naturalisation as a British citizen.

I hope the new law will target dishonest landlords who repeatedly fail to carry out Right to Rent checks by making it a criminal offence. This means they could face imprisonment for failing to check on their tenants. That is why more and more landlords are asking agents to manage their properties, so they can stay the right side of the law.
So what did our landlord do?


Well after our chat, he asked us to find a tenant and manage the property for him - he had seen my property blog and knew that we specialise in lettings.  Even better news for him, even though this would cost him agency fees, I was able to get him an additional £50 per month for his property (when we found him a tenant one week later). Now, together with the peace of mind we will keep him the right side of the law and put a stop to midnight phone calls complaining about dripping taps, it was a win-win situation for everyone.  www.meltonmowbrayproperty.com

Monday, January 18, 2016

Clydesdale Close - On the market for £140,000 this semi should see a 5% return

This 2 bedroom property is located on the north side of Melton Mowbray and is up for sale with Connells for £140,000. This property would easily let for £575 pcm with the current high demand for rental properties. 

This estate is popular with professionals commuting to Nottingham and Leicester. 

http://www.rightmove.co.uk/property-for-sale/property-39173343.html


Thursday, January 14, 2016

Elmhurst Avenue on the market for £134,950 - 5.1% potential return.


This 3 bed semi is marketed by Harrison Murray for £134,950. It looks to have been modernised and in a popular area with tenants. It has the potential for a garage and a large garden which should ensure capital growth. 

It should let for £575 pcm which, if you were to purchase it for the asking price, would give a yield of 5.1%.

http://www.rightmove.co.uk/property-for-sale/property-52150210.html


What does 2016 have in store for the Melton Mowbray Property Market?


Melton Mowbray house prices up or Melton Mowbray house prices down? ... and if so, by how much? Those of you who read the Melton Mowbray Property Blog will know I am not the sort of person who pulls punches nor someone who ever fails to give a forthright and straight talking opinion – so here are my thoughts for the 8,237 Melton Mowbray homeowners and landlords.

The average Melton Mowbray property is 3.1% higher today than it was a year ago, which doesn’t sound a lot, but when you consider inflation is currently running at -0.1% (ie consumer/retail prices are dropping) and average salary growth is only around 2.5% pa, this is bad news for first time buyers as property affordability continues to decrease (although I was reading in The Times the other day that wage inflation (ie salary growth) is showing signs of weakening).

Some commentators have said the higher stamp duty taxes announced a few weeks ago in the Autumn Statement for buy to let landlords, concerns over first time buyer affordability and the outlook of UK interest rate rises in 2016 will really dampen the property market. I hope you all read my previous article about what the new stamp duty rule changes would REALLY mean for Melton Mowbray landlords in my blog.

I believe the real issue in the Melton Mowbray property market is the shortage of property to buy, as people either worry there will be no suitable house to move to, or cannot afford to upgrade. However, on the supply side, Mr Osborne said in his Autumn Statement that he will change the planning laws to ensure the government meets the pledge made at the General Election (back in May) of 200,000 new homes a year.  All I can say is .. good luck George hitting those numbers!

Why? Because houses take years to build .. not months .. so George and his fabled house building aside .... where does that leave us in Melton Mowbray in 2016?

Well, talking of supply ... whilst Mr Osborne builds his properties (and let’s be honest - a week doesn’t go by without him being filmed on a building site with a high viz jacket and hard hat building a house here and there!), let us look at the shortage of properties for sale. Back in October 2011, 358 properties were for sale in Melton Mowbray .. today that figure is 143. On the face of it, this means there is less choice for Melton Mowbray buyers – but it also means with a restricted supply of properties for sale .. it keeps property prices high for Melton Mowbray house sellers.

Everything isn’t all doom and gloom though ... again back in October 2011, the average property in Melton Mowbray took 106 days to find a buyer .. latest figures state this has dropped to 82 days .. a drop of 23% in how long it takes to find a buyer. However, when you delve even deeper, the best performing type of property today in Melton Mowbray is the 4 bed, which only takes 75 days to find a buyer (on average) compared to the 1 bed, which takes 129 days. It just goes to show, even though the average has dropped since 2011, how varied that change has been!


So, back to the question everyone is asking .... What will happen to property values in Melton Mowbray in 2016?  I am going to suggest they will rise between 2.5% and 3.5% ... nothing out of the ordinary, but unless something cataclysmic happens in the world, 2016 will be like 2015! For more thoughts, opinions and views on the Melton Mowbray property market .. visit the Melton Mowbray Property Blog or drop me an email with properties you may be considering investing in and I will be happy to give you my honest opinion on their potential returns.

Thursday, January 7, 2016

Will the young people of Melton Mowbray ever own their own home?


I had the most interesting chat with a mature couple (in their early/mid 50’s) from Burton Lazars the other day, whilst viewing one of our rental properties. The property wasn’t for them, but their son. We got chatting about the Melton Mowbray property market and how they had bought their first property in the town just after they got married in the late 1980’s when they were in their early/mid 20’s.

Their son, like many 20 to 30 year olds in Melton Mowbray, desperately wants to own his own property. The parents said he had read in the Telegraph recently - when you compare house prices to earnings, the current 20 to 30 something’s generation have to spend more of their salary in mortgage payments than any previous generation. 

The demand for private rental sector accommodation in Melton Mowbray is huge. There are in fact 1,533 private rental properties in Melton Mowbray at the last count, not many when you consider there are 1,176 council houses in the town. However, let us not forget 8,237 properties are owner occupied (4,249 with a mortgage).

Private renting doesn’t have the stigma it had a few decades ago and it might surprise people that even though us Brit’s class ourselves as a nation of homeowners, roll the clock back 100 years and over 75% of people rented their home. It might also surprise you to learn that at the time of the 1971 census, still more people rented than owned their own home.

Looking at the affordability issue, I have proved time and time again, it is in fact cheaper to buy a property than rent, when one looks at starter homes for first time buyers. 95% mortgages have been available to first time buyers for over four years and whilst you could certainly find better properties in better condition in better areas, terraced houses can be bought for as little as the late £70,000’s in the Saxby Road area of Melton Mowbray (meaning a modest deposit of £4,000 would be required).

When it came to affordability, I was able to tell them that when they bought their first house in Melton Mowbray in 1988, the ratio of house prices to salary was 5.08 to 1 in Melton Mowbray ... and here was the surprise for both of us, today’s ratio is only 4.96 to 1!

I said I believed there had been a cultural attitude change towards renting property in Britain and that this quiet revolution was likely to be permanent. In the 60’s, 70’s and 80’s, buying a house was everything. Young people today have far much more disposal income than people had in the Callaghan and Thatcher years, but choose to spend it on the newest tablet or PC, newest 50” plasma LCD TV and two holidays a year, than go without and save for a deposit.

So with mortgage affordability being well within the bounds of most first time buyers, the level of deposit required for a 95% being surprisingly modest (starting off at c.£4,000 in Melton Mowbray as mentioned above) until we change our attitudes, the UK housing market is slowly but surely turning into a more European model, where people rent for long periods of their life, then eventually inherit their parents properties and subsequently become homeowners themselves, albeit later in life.

I cannot see the demand for decent, high quality rental properties ever dropping in the next 10 to 20 years, but only ever increasing as the population continues to soar. Just make sure you buy the right property, at the right price, in the right location.

For honest opinion on properties you might like to consider investing in please call me on 01664 569700 or pop into our office on Burton Street.

Wednesday, January 6, 2016

Proven 5% return on this town centre garden flat in Melton Mowbray

This ground floor, 1 bedroom flat is within walking distance of the town centre, and is in good condition.  Refurbished a few years ago, it is situated within a period conversion and has the added benefit of a garden.

Currently let out to a tenant at £395 pcm, it would see a return of around 5%.

The property is being marketed by Connells, and is listed as freehold.  I would say this requires some investigation before a purchase is made, as this is very unusual for a flat.

View full details here:

http://www.rightmove.co.uk/property-for-sale/property-57110837.html


Thursday, December 31, 2015

Asfordby Hill for sale at £106,000 - 6.2% return

This property is on the market for £106,000 with Melton Premier. It is a 2 bed terrace in an area that is popular with people renting due to the convenient location for commuting to Leicester and Nottingham and the primary school around the corner. 

We let properties on this road for £ 550 pcm and this should achieve that. This would give a potential return of 6.2%.

http://www.rightmove.co.uk/property-for-sale/property-44093758.html


Monday, December 21, 2015

Melton Mowbray House Price Monopoly: How do Prices vary?


Whether you are a homeowner or landlord in Melton Mowbray, what would a Monopoly board look like today in the town? Property prices over the last 80 years have certainly increased beyond all recognition, so looking at the original board, I have substituted some of the original streets with the most expensive and least expensive locations in Melton Mowbray today.

Initially, I have focused on the LE13 postcode only, looking at the Brown Squares on the board, the ‘new’ Old Kent Road in Melton Mowbray today would be Bramley Close, with an average value £48,400 (per property) and Whitechapel Road would be Drummond Walk, which would be worth £90,100. 

What about the posh dark blue squares of Park Lane and Mayfair? Again, looking at LE13, Park Lane would be Hunt Drive at £329,600 and Mayfair would be Kirby Lane at £420,200. However, look a little further afield from the LE13 postcode, and such roads as Pickwell Road in Leesthorpe would claim the Mayfair card at £765,000! 

Also, I can’t forget the train stations (my favourite squares), and over the last 12 months, the average price that property within a quarter mile of the station sold for was £215,950.

So that got me thinking what you would have had to have paid for a property in Melton Mowbray back in 1935, when the game originally came out?

  •         The average Melton Mowbray detached house today is worth £322,320 would have set you back 538 Pounds 3 shillings and 8 old pence.
  •         The average Melton Mowbray semi detached house today is worth £175,510 would have set you back 317 Pounds and 11 shillings.
  •         The average Melton Mowbray terraced / town house today is worth £148,680 would have set you back 269 Pounds and 1 old pence.
  •        The average Melton Mowbray apartment today is worth £118,590 would have set you back 214 Pounds 11 shillings and 3 old pence.

Anyway, I hope you enjoyed this bit of fun, but underlying all this is one important fact. Property investing is a long game, which has seen impressive rises over the last 80 years. 

In my previous articles I have talked about what is happening on a month by month or year by year basis and if you are going to invest in the Melton Mowbray property market, you should consider the Melton Mowbray property you buy a medium to long term investment, because Buy to let is pretty much what it sounds like – you buy a property in order to rent it out to tenants.

As I reminded a soon to be first time landlord from Thorpe Arnold the other week, Buy to let in Melton Mowbray (as in other parts of the Country) is very different from owning your own home. When you become a Melton Mowbray landlord, you are in essence running a small business – one with important legal responsibilities. 

On that note, I want to remind landlords of the recent and future changes in legislation when it comes to buy to let. This year, rules have changed about tenant deposits, carbon monoxide detectors and early in the New Year, landlords will have responsibilities to do immigration checks on all their tenants. Failure to adhere to them will mean a minimum of heavy fines in the thousands or in some cases, prison ... it’s a mine field!  

That’s why I write the Melton Mowbray Property Blog, where it has an extensive library of articles like this one, where I talk about what is happening in the Melton Mowbray property market, what to buy (and sometimes not) in Melton Mowbray and everything else that is important to know as a Melton Mowbray landlord. 

Thursday, December 17, 2015

Asfordby potential 5.5% return

I have overlooked this property on the market with Harrison Murray as I have not seen many houses on this street come up for sale and be presented so nicely. This one inside has been really well finished and is on the market for £120,000.

It would let for £550 pcm giving a potential return of 5.5%. Definitely worth a viewing.

Click on the link to look at the floor plan...


The Melton Mowbray Property Market and £1,300,000,000,000,000,000 in loose change


The 5th of March 2009 was the date Mervyn King, the then Bank of England Governor, slashed UK interest rates to the unparalleled figure of 0.5%. 

In just under five months, starting on 8th October 2008, the rate had come down from 4.5% to that low figure, all in an attempt to ensure the British economy survived the worldwide credit crunch. Now as we deck the halls with bows of holly nobody expected that, over six years later, rates would still be at that low level.

In the summer, people were predicting a rise in the New Year, yet now, some forecast it may remain the same for years to come the due to the issues in China. 

What I do know, speaking to my Melton Mowbray friends and Melton Mowbray landlords is that these low interest rates have hit savers really hard.

If you added up everyone’s bank and building society savings in the UK, they would add up to £1,300,000,000,000,000,000 (that’s £1.3 trillion), most of which is earning a pittance in interest.  That is why more and more 40 and 50 year old Melton Mowbray landlords have been investing some of that cash into Melton Mowbray bricks and mortar, as they search for a low risk investment opportunity.

Buying a Melton Mowbray buy to let property isn’t risk free, but there are certainly things you can do to mitigate and lower one’s exposure to risk. You see by buying a rental property, it potentially offers a decent proposition in terms of being able to obtain attractive returns that beat inflation and savings accounts, yet without taking the levels of risk associated with stock markets.

The UK residential property market has long been the safest form of collateral for lenders of all varieties. Against a backdrop of a greatly changing economic environment, Melton Mowbray house prices have been extraordinarily robust, increasing by over 1715.3% between 1974 and today. Some will say there have been significant property price falls, namely in 1975, 1988 and 2008, yet each time after this has been followed by an upturn in property values. For the record, the stock markets in the same time frame only rose by 432.5%!

.. and that is the best thing about buy to let property. Unlike the stock market, with its unfathomable equities, shares and bonds, that nobody really understands (as they are controlled by some faceless whizzkid in Canary Wharf!) with a buy to let property, landlords can take control and understand their investment .. in fact you can touch and feel the bricks and mortar investment.

..  but before you go out and buy any old Melton Mowbray property, plenty of landlords still get it wrong. You have to be aware of your legal responsibilities when it comes to tenant safety, tenants deposits, energy certificates and in the new year, landlords will have the added responsibility of checking the immigration status of prospective tenants. Get it wrong and big fines and even prison is an option – but that’s why many agents use a letting agent to manage their property for them.

Next, you have to buy the right property at the right price. Recently I have seen some really heart breaking situations in Melton Mowbray and the immediate area, of people paying way too much for a property, only to lose out when they came to sell. One example that comes to mind is that of a property owner in an apartment on Buttermere Close (just off the A607) .. a decent, well presented, two bed, ground floor, apartment, 54 sq metres inside (581 sq ft in old money) sold in October 2006 for £110,700. In the summer, it only obtained £100,000, a drop of 9.67% or 1.15% a year - a very disappointing result.

I cannot stress enough the importance of doing your homework. One source of information and advice is the Melton Mowbray Property Blog or please pick up the phone and give me a call, I am always happy to talk about the Melton Mowbray Property market!

Thursday, December 10, 2015

Has Osborne killed the buy to let market in Melton Mowbray?


Well George Osborne, in his Autumn statement, caused Melton Mowbray landlords to ask whether buy to let is a viable investment option, when he announced that landlords, when buying another buy to let property from April 2016 will have to pay an additional 3% stamp duty on top of the standard rate.  

So if an investor wanted to buy a property in Melton for £123,000, before they would not have had to pay a penny in stamp duty, but from April next year it will be  £3,690. Move up market and it means that the stamp duty bill for a £285,000 buy to let home will rise from the current £4,250 to £12,800 from April next year. 

Some say property in Melton Mowbray will be worth less because potential landlords will not be willing to pay as much for them, and if house builders or existing homeowners don't feel they are going to get as much for them, then there is less motivation to build / sell them?... and the person we can blame for this is George himself. Back in 2012, he chose to utilise the British housing market to kick start the UK economy, with  subsidies, Funding for Lending and Help to Buy.

Others say this is the straw that breaks the camel’s back as over the next four years Landlords will slowly lose the ability to offset all their mortgage interest against tax on rental income, after changes announced in the Summer Budget. At the moment, landlords can claim tax relief on buy to let mortgage monthly interest repayments at the top level of tax they pay (ie 40% or 45%). 

However, over the next four years this will be reduced slowly to the basic rate of tax – currently 20%.
Surely this is the end of Buy to Let in Melton Mowbray? Probably.. but before we all run to hills panicking .. let me give you another thought.

Stamp Duty rules were changed in December 2014. Before then, landlords were eagerly buying up properties under the ‘old slab style Stamp Duty’ system. For example, the stamp duty bill on that £285,000 property was lower on the old slab style duty (pre Dec 2014), at £8,550, yet it isn’t a million miles away from new £12,800 stamp duty bill. Interestingly though, George has left a legal loophole in the new rules, because when it comes to selling up, they can offset purchase costs against any eventual capital gains tax, including stamp duty.

I believe that total returns from buy to let will continue to outpace other investments, such as the stock market, gilts, bonds and even pensions. Also, the best part about investing in property is that it is bricks and mortar. You can touch it, you can feel it, and it isn’t controlled by some City whiz kid in Canary Wharf .. the British understand property and that goes a long way!


Buy to let has enough impetus behind it that prospective landlords will continue to buy even with a larger stamp duty bill. Melton Mowbray landlords will need to be savvy with what property they buy to ensure the extra stamp duty costs are mitigated.   Buying buy to let property is a long term venture. 
Now with these extra taxes, the adage of ‘any old Melton Mowbray house will make money’ has gone out the window.   You wouldn’t dream of investing in the stock market without at least looking in the newspapers or taking advice and opinion from others, so why wouldnt you take the same advice and opinion about buying a buy to let property in Melton Mowbray? please feel free to give me a call for honest, unbiased advice on potential buy to let investments. 01664 569700

Wednesday, December 9, 2015

Blyth Avenue - great investment for sale at £125,000

This property has been listed by Harrison Murray and is on the market for just under £125,000. Although it has a shower room it would easily let for £550 pcm - potential 5.2% return. 

These types of properties are popular with professional couples as they are a nice size and have a manageable garden.

http://www.rightmove.co.uk/property-for-sale/property-52344043.html


Thursday, December 3, 2015

Melton Mowbray Property Market Values


Many landlords have been asking me my thoughts on the Melton Mowbray property market recently, and in particular, what is happening to property values.   My calculations show property values in Melton Mowbray grew in the month of September by 1.9%.   

When one looks at the annual growth, Melton Mowbray values are 6.9% higher (when comparing Sept 14 to Sept 15), impressive when you consider the annual growth of property values dropped to only 0.7% per annum in May.   

There are signs, however,  that the fundamental growth of property values in Melton Mowbray has now peaked, despite those average property values being below levels recorded in 2007 (just before the 2008 crash).

Whilst the Melton Mowbray headline rate appears to be better, i.e. the year on year (Sept 14 to Sept 15) growth rate of 6.9% is obviously better than the drop of 0.7% in May 14 to May 15), this impressive rise of Melton Mowbray property values masks the underlying truth in what is really happening to local property values in the town.  

Throughout 2015, property values have been yo-yo like on a month by month basis, for example,
  •          September 2015             1.9% rise
  •          August 2015                   0.2% rise
  •          July 2015                       2.3% rise
  •          June 2015                      0.4% rise
  •          May 2015                       0.3% drop
  •          April 2015                      0.4% drop
  •          March 2015                    2.7% drop

This is in part due to seasonal factors, as well as mortgage approvals increasing over June and July then falling by over 15% in August, according to the Council of Mortgage Lenders (CML).

The outlook for the Melton Mowbray property market remains positive against the foundations of low mortgage rates and growing consumer confidence. 

On a positive note, Melton Mowbray property values are still running ahead of salaries and average property values are 5.1% below the levels recorded in 2007.

Readers might be interested to note that before the 2008 property crash, all the UK region’s housing markets tended to move up and down in tandem.   Since then though, the Greater London property market took off like a rocket in 2009/10, whilst the rest of the UK only really started to grow in 2012/13, and even then that growth was a lot more modest than the Capital’s.  

Looking closer to home, it can even be different in neighbouring towns, areas and cities, so whilst Melton Mowbray property values are 6.9% higher than a year ago, Leicester property values are 4.1% higher than a year ago.

I cannot stress enough the importance of doing your homework.  

One source of information and advice is the Melton Mowbray Property Blog where I have similar articles to this about the Melton Mowbray property market and what I consider to be the best buy to let deals around at any one time in the town, irrespective of which agent it is on the market with.  please feel free to give me a call 01664 569700

Wednesday, December 2, 2015

Modern 3 bed new to the market - Valiant Way, Melton Mowbray

As I have mentioned before, nearly new homes make a wise investment choice.  Always popular with tenants, with little maintenance, plus warranties in case things do go wrong, here is a great example of such a property.  

Being marketed by Connells, this is a 3 bed property situated on a popular development close to good schools and within walking distance of the town centre.

Looks to be in good order so should be a quick and easy process to letting your next investment property.

Full details can be found here:

http://www.rightmove.co.uk/property-for-sale/property-56322002.html


Thursday, November 26, 2015

Values of Melton Mowbray Terraced Houses smash through the £190/sqft barrier


The Council of Mortgage Lenders (CML) latest snapshot of the buy to let mortgage market shows us that buy to let landlords haven’t been put off by the Chancellors announcements on the way buy to let’s are taxed.

Last month, the CML stated £1.4billion was borrowed by UK landlords to purchase 10,500 buy to let properties, up 26.5% from the same month in 2014, when only 8,300 properties were bought with a buy to let mortgage. Go back two years and the number of buy to let mortgages used for purchasing (again not re-mortgaging) is 36.4% higher! Even more interesting has been the fact that the average amount borrowed has risen as well. The average buy to let mortgage last month was £133,330, up from £128,480 a year ago.

In Melton Mowbray, I am speaking to more and more landlords, be they seasoned professional landlords or FTL’s (first time landlords), as they read reports that the Melton Mowbray rental market is doing reasonably well, with rents and property values rising.  Interestingly, one landlord recently asked how much he should be paying per square foot (more of that in a second).

The first thing you have to decide is whether you want great capital growth or great rental yield, as every knowledgeable landlord knows, you can’t have both. Over the last twenty years, property values in Melton Mowbray have risen by 160.31%, compared to Greater London’s 436.2%. This has proved that capital growth increases faster in the more expensive South, but your investment money doesn’t go very far, meaning there won’t be as much rental yield from a 1 bed flat in Chelsea (2% per year at best with a fair wind) as a 2 bed semi in Melton Mowbray. However, whilst the figure of 160.31% is an average for the area, certain areas of Melton Mowbray have seen capital growth much higher than that and others areas much worse (we have talked about those in previous articles).

If you recall in an earlier article, my research reveals that Melton Mowbray apartments tend to generate a better yield than houses, probably because several sharers can afford to pay more than a single family. But houses tend to appreciate in value more rapidly and may well be easier to sell, simply because there are fewer being built.

So what should you be buying in Melton Mowbray, and more importantly, how much?

  •         The average apartments in the town are currently selling for approximately £144 per square foot.
  •         Terraced houses in Melton Mowbray are currently obtaining, on average, £145,900 or £190 per square foot,
  •          An average semi in Melton Mowbray is selling for £172,200 (and achieving £187 per square foot). 


Now these are of course averages, but it gives you a good place to start from. In the coming weeks, I will look at rents being achieved on Melton Mowbray houses and apartments, and the yields that can be obtained, depending how many bedrooms there are. 

Thursday, November 19, 2015

Melton Mowbray Buy To let –Freehold House or Leasehold Flat?


Well my Melton Mowbray Property Blog reading friends, as seems to be all the rage with Jeremy Corben asking the PM questions emailed in to him at Prime Minster Question Times, I to wish to answer a question emailed into me from a potential Melton Mowbray landlord last week. Nice chap, lives in Thorpe Arnold, and it turns out, after having a coffee with him, he works in IT, has a spare bit of cash (now the kids have flown the nest) and wanted to buy his first buy to let property.

His main question was ... Do I buy a freehold house or a leasehold flat in Melton Mowbray?

Most people will say freehold every time, because you own the land. However, it’s not as simple as that (it never would be would it!). The definitive answer though is to research what Melton Mowbray tenants want in the area of Melton Mowbray they want! The tenant is ultimately your customer, and, if they don't want to rent what you decide is best to buy, then you are not going to have a successful BTL investment. So starting with the tenant in mind and working backwards from there, you won’t go far wrong. In a nutshell, find the demand before you think about creating the supply.

Leasehold flats and apartments in Melton Mowbray are excellent in some respects as they offer the landlord certain advantages, including the fact a flat can be initially cheaper to buy. Yields can be quite good, offering better cash flow. The building will already be insured and yes there is a service charge, but it’s still for a service at the end of the day and that cost is spread between many others (i.e. when your freehold house roof goes, its falls 100% on your shoulders) and one of my favourites is that there is often no garden to maintain or blown down fences to replace!

However, some Melton Mowbray leasehold flats can suffer from poor capital growth. Some leasehold properties have no cap on the level of the service charge and it may get out of control. The length of the lease will significantly affect value if not renewed before it gets too short. Thankfully there’s not many, but some Melton Mowbray apartments/flats have burdensome clauses. Finally, with leases, there can be sub-letting issues – which means you can’t let them out.

So what do the numbers look like? Well since 2003, the average freehold property in Melton Mowbray (detached, semis and terraced) has risen from £113,357 to £179,358, a rise of 58% whilst the average Melton Mowbray leasehold property (flats and apartments) has gone up in value from £62,498 to £114,950, a greater rise of 84%. 

I was really interested to note that of the 2,738 rental properties in the Melton Borough Council area that the Office of National Statistics believe are either let privately or through a letting agency, 476 of them (or 17.4%) are apartments. However, there are only 1,622 apartments in the whole council area (be they owned, council rented or privately rented), which represents 7.5% of the whole housing stock in the area. This really intrigued me that, quite obviously, there is a high proportion of Melton Mowbray’s leasehold apartments/flats rented to tenants compared to detached, semi’s or terraced. Fascinating don’t you think?

Every Melton Mowbray apartment block, every terraced house or semi is different. Like I said at the start, the definitive answer though is to research what Melton Mowbray tenants want in the area of Melton Mowbray they want. Demand for town centre apartments, near transport links can be popular and can offer the Melton Mowbray landlord very good yields with minimal voids. However, Melton Mowbray terraced houses and semis, whilst not always offering the best yields (although sometimes they can), they do offer the Melton Mowbray landlord decent capital growth.

My advice to the prospective landlord as it is to you is do your homework.  What many Melton Mowbray landlords do, irrespective of whether you are a landlord of ours, a landlord with another agent or a DIY landlord, if you see any property in Melton Mowbray, that catches your eye as a potential buy to let property, be it a terraced house, semi or flat ... email me and I will email you back with my thoughts (although I will tell you what you need to hear .. not want to hear!)


Friday, November 13, 2015

6% return on a £95,000 investment

For sale with Richard Watkinson a great property that could provide a 6% return. 

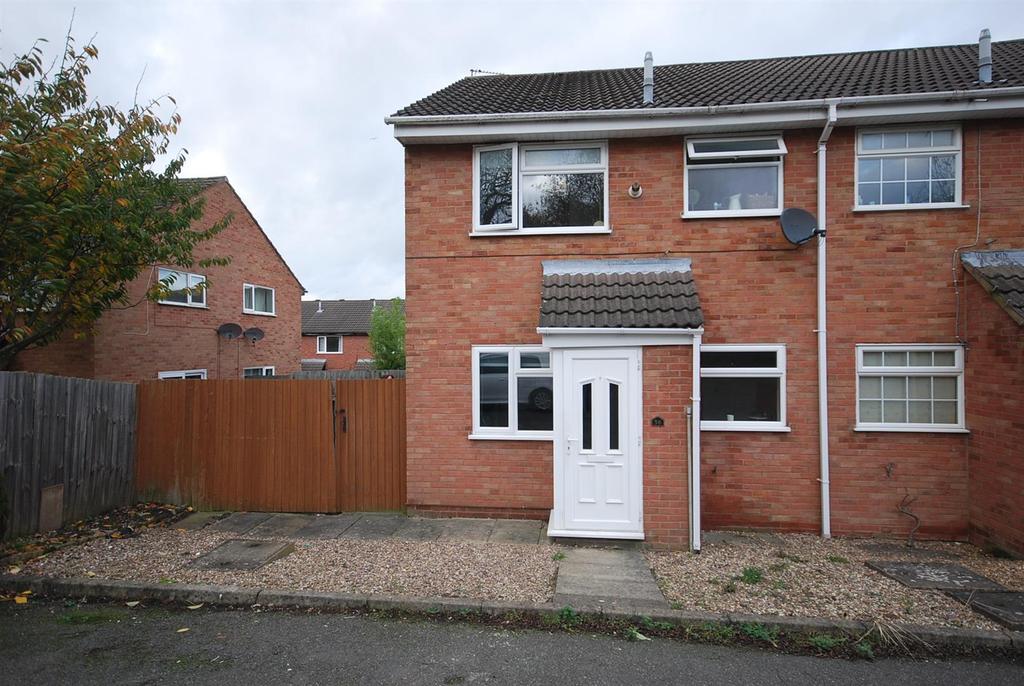
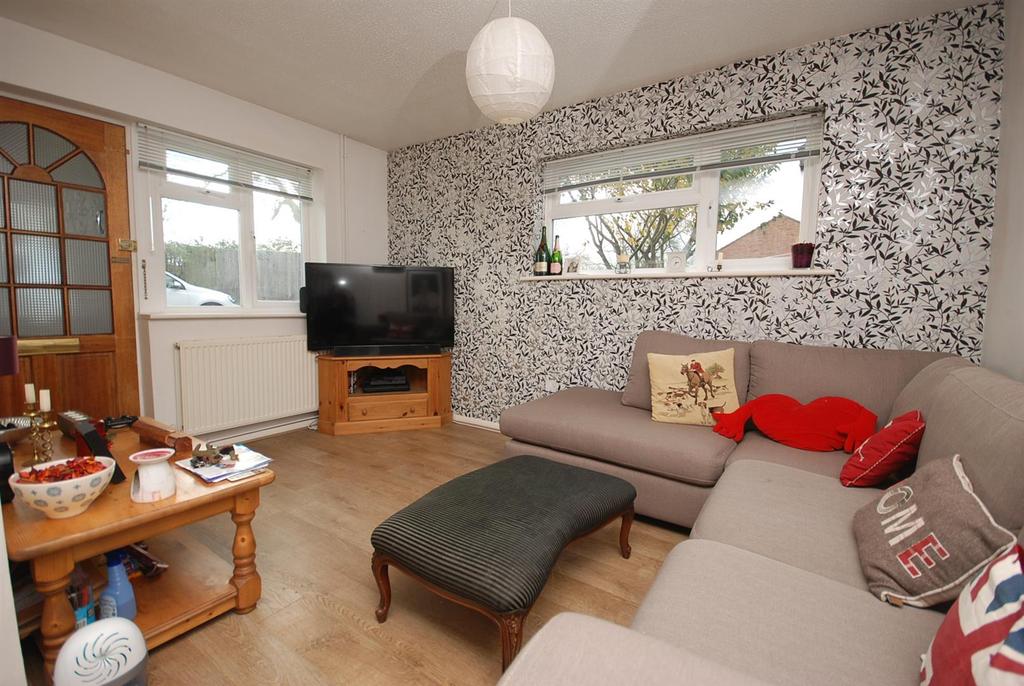
These quarter houses really let well for £475 pcm. This one has a lovely kitchen and bathroom that will appeal to a professional tenant. It is on the market for £95,000 and looks to be in good condition. 


Image 1 of 9: Front1.JPG

Image 2 of 9: Lounge.JPG